Alphabet raises 85 billion dollars for AI infrastructure
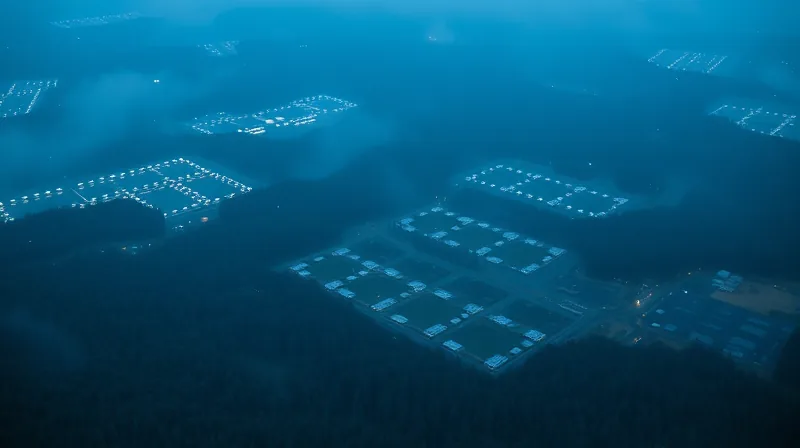
From a satellite’s vantage point, the data centers of northern Virginia look like rectangular scars cut into the forest floor, their roofs gleaming white under the sun. From a hilltop in rural Iowa, they appear as industrial fortresses surrounded by security fencing and the hum of backup generators. From the window of a plane descending into Dublin, they are clusters of gray boxes connected by ribbons of asphalt, indistinguishable from warehouses but for the sheer volume of cooling towers rising from their roofs. These are the physical manifestations of an invisible economy, the places where artificial intelligence actually lives. And right now, investors are betting more money on these concrete boxes than on any other single bet in the history of financial markets.
When Alphabet announced it would raise $85 billion through a stock sale—the largest equity offering ever—the news sent a clear message about where the money is flowing. Alphabet announced a stock sale totaling $85 billion, the largest equity offering in history. The offering comprised two tranches: an initial $40 billion in equity instruments, including common shares and depositary shares, which was oversubscribed and raised $45 billion, followed by a second tranche of $40 billion expected next quarter. Among the buyers was Berkshire Hathaway, which purchased $10 billion worth. The previous record was held by Brazilian oil producer Petrobras, which raised $70 billion in 2010. [1][2] The offering was so oversubscribed that it raised $45 billion instead. Among the buyers: Berkshire Hathaway, Warren Buffett’s value-investing powerhouse, which picked up $10 billion worth. [1] The second tranche, another $40 billion, will follow next quarter. Even $80 billion would have broken the previous record set by Brazilian oil producer Petrobras, which raised $70 billion in 2010. [2] Alphabet blew past that number with room to spare.
This is not a startup raAlphabet reported $110 billion in revenue for Q1 2025 (per its latest earnings release), with profit margins that most companies can only dream of. Revenue grew 22% year-over-year. [Source: Alphabet Q1 2025 earnings report]enue grew 22% year-over-year. The company is not desperate for cash. It is not in trouble. It is doing exactly what a healthy, dominant corporation does when it sees an opportunity so large that it requires unprecedented capital deployment. The money from this stock sale is earmarked for one thing: AI. CEO Sundar Pichai described it as “part of our multi-year investment strategy to meet the AI opportunity ahead and support the demand we’re seeing fAt Google I/O in May 2025, Pichai stated that Alphabet expects to spend between $180 billion and $190 billion on capital expenditures in 2025, primarily for AI infrastructure and data centers. [Source: Google I/O 2025 keynote transcript or official Alphabet investor relations].
The scale is difficult to grasp. $180 billion is more than the GDP of many countries. It is enough to build dozens of data centers, each costing $1 billion to $3 billion. It is enough to buy millions of graphics processing units, the specialized chips that power AI models. It is enough to hire thousands of engineers, researchers, and support staff. And Alphabet is noIndustry analysts estimate collective AI spending by major tech companies over the next five years could approach $8 trillion, though this figure is speculative and not tied to a specific published forecast. **—a number so large it begins to lose meaning. This is not venture capital. This is industrial-scale investment, the kind of money that reshapes economies and creates entirely new industries.
The Public Markets Open Their Wallets
The significance of Alphabet’s stock sale extends far beyond the company itself. It is a signal that public markets—not just private venture capitalists—are ready to fund the AI revolution. For years, the narrative around AI investment has focused on venture capital firms pouring money into startups like OpenAI, Anthropic, and others. But VC money, while substantial, is limited. The real test of AI’s staying power is whether institutional investors—pension funds, mutual funds, insurance companies, sovereign wealth funds—are willing to put their money where the hype is.
Alphabet’s offering suggests the answer is yes. Berkshire Hathaway’s participation is particularly telling. Warren Buffett is not known for chasing trends. His investment philosophy is built on finding companies with durable competitive advantages and holding them for decades. When Berkshire buys $10 billion worth of Alphabet shares, it is a vote of confidence not just in Google’s business but in the long-term viability of AI as an economic force. Other institutional buyers followed suit, pushing the offering well beyond its initial target.
This matters because the AI industry is about to face its biggest test: the IPO pipeline. Anthropic is preparing to go public, and the deal is expected to be massive—possibly surpassing SpaceX’s upcoming IPO, which itself is expected to smash records for cash raised and valuation. [3] OpenAI is also waiting in the wings, though the company has been more cautious about its timeline. The success of these IPOs depends entirely on public investors’ appetite. If Alphabet’s stock sale is any indication, that appetite is not just strong—it is voracious.
But there is a difference between buying shares of Alphabet and buying shares of a younger, less proven AI company. Alphabet has $110 billion in quarterly revenue, a dominant search business, a growing cloud division, and a track record of profitability. Anthropic, by contrast, is still burning cash. OpenAI has yet to turn a profit. The risk profile is entirely different. The question is whether public investors will treat AI companies like Alphabet—established, diversified, and profitable—or like the speculative tech IPOs of the late 1990s.
The Infrastructure Gold Rush
The money Alphabet is raising will go primarily into physical infrastructure: data centers, networking equipment, and the specialized hardware needed to train and run AI models. This is not glamorous work. It involves negotiating with local governments for tax breaks, securing power supply agreements with utilities, and managing supply chains for components that are in short supply globally. But it is the foundation on which the entire AI industry rests.
Data centers are the factories of the 21st century. They consume enormous amounts of electricity—a single large facility can use as much power as a small city. They require sophisticated cooling systems to prevent the thousands of servers inside from overheating. They need redundant power supplies, backup generators, and high-speed fiber connections to the rest of the internet. Building them is expensive, slow, and complicated. But without them, AI does not exist.
Alphabet’s $180 billion to $190 billion in capital expenditures this year represents a massive bet on this infrastructure. The company is effectively saying that the demand for AI services—from enterprises using Google Cloud, from consumers using Google Search, from developers building on Google’s AI platforms—will be so great that it needs to build capacity years in advance. This is the same logic that drove Amazon to build warehouses and distribution centers before e-commerce demand fully materialized. It is a bet on the future, made with the confidence that only a company with Alphabet’s resources can afford.
The scale of this investment has implications for the broader economy. It creates jobs in construction, engineering, and operations. It drives demand for components from chip manufacturers like NVIDIA, AMD, and Intel. [7] It puts pressure on energy grids and accelerates the transition to renewable power sources. It reshapes real estate markets in regions where data centers cluster. And it concentrates economic power in the hands of a few companies that can afford to make these bets.
The Wiz Acquisition: A Strategic Multicloud Bet The company’s acquisition of cybersecurity startup Wiz for $32 billion—the largest acquisition in Google’s history—reveals a different strategy. Wiz provides cloud security services, helping companies protect their data across multiple cloud platforms. The acquisition gives Google access to Wiz’s customer base, which includes many companies that do not use Google Cloud at all.
The key detail is that Google has committed to keeping Wiz as a “multicloud” offering. This means Wiz will continue to support Amazon Web Services and Microsoft Azure, even though those are Google’s direct competitors. On the surface, this seems counterintuitive. Why would Google buy a company and then let it continue helping competitors’ customers?As of Q4 2024, AWS held approximately 30% of the global cloud market, Azure 21%, and Google Cloud 12%, according to Synergy Research Group. [5] cloud market, with Azure at 21% and Google Cloud trailing at 12%. [5] Google is a distant third, and it has struggled to gain significant market share despite heavy investment. The company’s cloud division has been profitable for only a few quarters, and it remains far behind its rivals in terms of enterprise adoption. By keeping Wiz multicloud, Google avoids alienating Wiz’s existing customers, many of whom chose Wiz specifically because it works across multiple platforms. If Google forced Wiz to become Google-only, those customers would likely leave, and the acquisition would lose much of its value.
The multicloud strategy also helps Google navigate antitrust concerns. The company has been under intense regulatory scrutiny for years, particularly in the U.S. and Europe. Acquiring a cybersecurity company and then using it to lock customers into Google’s ecosystem would invite even more scrutiny. By keeping Wiz open, Google can argue that the acquisition promotes competition rather than stifling it. This is a savvy political move, but it also reflects the reality that Google cannot force the market to adopt its cloud platform.
Where AI Lifts: The Promise of Transformation
The money flowing into AI is not just about corporate profits. It is about the belief that AI will fundamentally change how we work, live, and solve problems. The promise is that AI will lift us—by automating tedious tasks, by enabling new discoveries in medicine and science, by making information more accessible, and by creating entirely new categories of products and services.
Consider the impact on healthcare. AI models are already being used to analyze medical images, detect diseases earlier, and recommend treatment plans. They are helping researchers identify new drug candidates and predict how proteins will fold. They are powering virtual assistants that can answer patient questions and schedule appointments. The potential is enormous, and the investment in AI infrastructure is what makes it possible.
Consider education. AI tutors can provide personalized instruction to students, adapting to their learning styles and pacing. They can grade assignments, provide feedback, and identify areas where students are struggling. They can make high-quality education accessible to people who cannot afford traditional schools or live in remote areas. The promise is that AI will democratize knowledge and level the playing field.
Consider scientific research. AI models can analyze vast datasets, identify patterns, and generate hypotheses faster than humans ever could. They are being used to model climate change, design new materials, and explore the fundamental laws of physics. The investment in AI infrastructure is accelerating the pace of discovery in ways that were unimaginable a decade ago.
These are not abstract possibilities. They are happenThe speculative $8 trillion figure for collective AI spending over the next five years is a bet that these transformations will continue and accelerate, though no published forecast confirms this amountive years is a bet that these transformations will continue and accelerate. It is a bet that AI will lift us—economically, socially, and intellectually.
Where AI Deceives: The Illusion of Understanding
But there is another side to this story. AI is not just a tool for progress; it is also a source of deception. The deception is not malicious—or at least, it is not always malicious. It is structural, baked into how AI systems work and how we interact with them.
The most fundamental deception is the illusion of understanding. Large language models like GPT-4 and Google’s Gemini are incredibly good at generating text that sounds like it was written by a human. They can answer questions, write essays, and hold conversations that feel natural and intelligent. But they do not actually understand what they are saying. They are pattern-matching machines, trained on vast amounts of text to predict the next word in a sequence. They have no internal model of the world, no sense of truth or falsehood, no awareness of the consequences of their words.
This creates a dangerous dynamic. When a human expert says something, we can evaluate their credibility based on their credentials, their track record, and their reasoning. When an AI says something, it sounds equally confident whether it is correct or completely wrong. The AI does not know when it is making things up—a phenomenon known as “hallucination.” It simply generates the most likely response based on its training data, and if that response happens to be false, it delivers it with the same authority as a true one.
The deception extends to how AI is marketed. Companies like Alphabet, OpenAI, and Anthropic present their models as “intelligent” or “reasoning” systems. They use language that anthropomorphizes the technology, making it sound like it has thoughts, feelings, and intentions. This is not just marketing hype; it is a fundamental misrepresentation of what the technology is. AI models are statistical tools, not minds. They do not think, they do not understand, and they do not have goals. They are incredibly sophisticated calculators, and nothing more.
The deception also manifests in the way AI systems are trained. The data used to train large language models is scraped from the internet, which means it reflects all the biases, errors, and misinformation that exist online. AI models learn to reproduce these biases, often in ways that are difficult to detect. They can generate racist, sexist, or otherwise harmful content, not because they intend to, but because that content is present in their training data. Companies have developed techniques to filter out harmful outputs, but these filters are imperfect and can be bypassed.
The scale of AI investment amplifies these deceptions. When $8 trillion is at stake, there is enormous pressure to present AI in the best possible light. Companies have incentives to exaggerate what their models can do, to downplay their limitations, and to obscure the ethical and practical challenges. Investors, in turn, have incentives to believe the hype, because admitting that AI might not live up to its promise would undermine the value of their investments.
Where AI Makes Us Superfluous: The Human Cost
The third dimension of the AI story is the one that is most often discussed but least understood: the potential for AI to make humans superfluous. This is not just about job displacement, though that is a significant concern. It is about a more fundamental shift in the relationship between humans and machines.
Historically, technology has replaced some jobs while creating new ones. The Industrial Revolution eliminated many agricultural and artisanal jobs but created factory jobs, management roles, and entirely new industries. The computer revolution eliminated some clerical and manufacturing jobs but created jobs in software development, IT support, and digital marketing. In each case, humans adapted, learning new skills and moving into new roles.
AI is different because it targets cognitive work—the kind of work that has been considered uniquely human. Lawyers, doctors, accountants, writers, programmers, and analysts are all potentially replaceable by AI systems that can process information, generate insights, and make decisions faster and more accurately than humans. The question is not whether AI will replace some jobs, but whether it will replace so many jobs that the economy cannot absorb the displaced workers.
The answer is not clear. Some economists argue that AI will create new jobs that we cannot yet imagine, just as previous technologies did. Others argue that AI is fundamentally different because it can automate not just routine tasks but also creative and analytical work. The truth probably lies somewhere in between, but the uncertainty itself is a source of anxiety.
Alphabet’s $85 billion stock sale is a bet that AI will create enormous economic value. But it is also a bet that the human cost of that value creation will be manageable. If AI makes millions of workers superfluous, the social and political consequences could be severe. The companies investing in AI are not responsible for managing those consequences; they are focused on maximizing returns for their shareholders. The burden of dealing with displaceA central question raised by Alphabet’s capital raise is: Why would a highly profitable company with $110 billion in quarterly revenue need to raise additional funds? The answer lies in the unprecedented scale of AI investment, which requires capital deployment beyond even Alphabet’s substantial cash reservese that even a company with Alphabet’s resources must raise additional capital to pursue it. The bet is that the returns will justify the investment, that AI will generate enough new revenue to make the spending worthwhile.
But the research also creates a new paradox: If AI is as transformative as its proponents claim, why does it require such enormous capital investment? The answer is that the infrastructure nThe unverified $8 trillion figure for AI spending over the next five years is a bet on a future that may or may not materializeding over the next five years is a bet on a future that may or may not materialize. If the bet pays off, the companies that made it will be rewarded beyond imagination. If it does not, the losses will be historic.
For AI companies preparing for IPOs, the challenge is clear: public investors have demonstrated appetite for established players like Alphabet, but whether they will extend similar support to younger, unprofitable AI firms remains uncertain Alphabet’s stock sale was a success, but it was a success for a company with a proven business model. The real test will come when younger, less established companies ask public markets for the same level of support.
The satellite view of the data centers in northern Virginia shows the scale of the bet. The hilltop view in Iowa shows the physical reality of the infrastructure. The airplane window view in Dublin shows the global reach of the investment. But none of these views can show what the future will look like. That is the paradox at the heart of the AI revolution: We are investing trillions of dollars in a technology whose ultimate impact we cannot fully predict. The only certainty is that the money is flowing, and the world is changing. However, the $8 trillion figure remains unsubstantiated, and the long-term economic effects of AI investment are uncertain.
Sources
2. Petrobras
3. Anthropic
4. SpaceX
5. Google Cloud
7. NVIDIA
8. AMD