US Profit Forecasts Raised Before Earnings Season
Our own tape speaks first
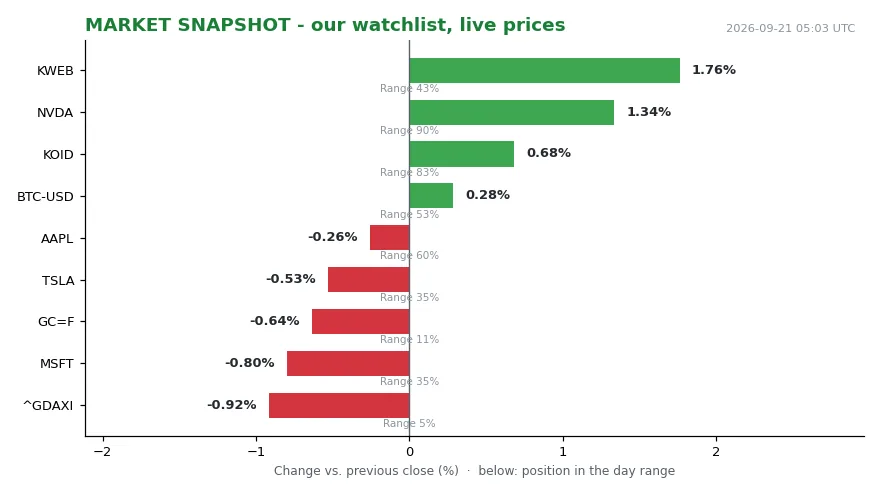
Nine assets, one snapshot, taken at 04:59 UTC on September 21, 2026.
NVIDIA prints 222.27 dollars, up 1.34 percent against the previous close, and sits at 90 percent of the low-to-high span of the session’s prices. That is the top edge of the session. KWEB, a basket of Chinese internet names, adds 1.76 percent and holds near the middle of its low-to-high span at 43 percent. KOID, another watchlist name, rises 0.68 percent, near day highs at 83 percent of the low-to-high span. Apple slips 0.26 percent and sits near the middle of its low-to-high span at 60 percent. Microsoft loses 0.80 percent, at 35 percent of its low-to-high span. Tesla loses 0.53 percent, also at 35 percent. Bitcoin trades at 81,421.07, up 0.32 percent, near the middle of its low-to-high span at 56 percent. Gold falls 0.59 percent to 4,398.70, near day lows at 18 percent of the low-to-high span. The DAX drops 0.92 percent to 25,304.06, near day lows at 5 percent.
So silicon and one China proxy lead. European equities and gold in bar form lag. Mega-cap software drifts sideways. That pattern is money moving from one sector into another, not panic. It is also narrow, and narrowness is a fact worth carrying into the rest of this piece.
The tape is quiet: no single name is moving violently, and the dispersion between the strongest and weakest of the nine is under three percentage points. That narrowness is the fact worth carrying into the rest of this piece.
The map arrives before the walk
Now the map: FactSet’s Earnings Insight report, with data as of September 18, 2026. Its subject is the July-to-September quarter of 2026, the period US companies begin reporting in October. S&P 500 profits are expected to rise about 29 percent compared with the same period a year earlier. [1] If that lands, it becomes the third consecutive quarter above 25 percent. Sales are expected to grow roughly 12 percent. So the expansion is not margin alone; sales are growing too.
The expectation behind these numbers is simple: that the largest listed companies in the world are still getting bigger and more profitable at the same time. That expectation is why the report circulates before the season even opens.
The channel is revision, not level
The mechanism that matters is revision, not level. Analysts usually start a quarter optimistic and end it humble. Over the past five years, forecasts have been trimmed by roughly 2 percent during the period. That is the standard slope: down and to the right. This time the number moved the other way. Three months ago the estimate was about 27 percent; it is now about 29 percent.
Guidance is the second channel. Of 115 companies that issued outlooks, more than 60 percent guided above analyst forecasts. The five-year average sits near 40 percent. The companies themselves are leaning positive, not defensive.
Efficiency is the third channel. The net profit margin—profit remaining per dollar of sales—is expected at 15 percent, meaning fifteen dollars remain from every 100 dollars of sales. That is the second-highest level since records began in 2009. The record was 17 percent in the April-to-June quarter of 2026, a period in which nearly 90 percent of companies beat forecasts.
Valuation is the fourth channel, and it runs the other way. The S&P 500’s price is 19.1 times forecast profit per share, down from 20.4 times three months ago. The five-year average is 19.8 times. The ten-year average is 19.0 times. So the index has drifted back toward something like “moderate”. The average of analysts’ price targets sits roughly 21 percent above the current level, though targets skew bullish from the start and belong in the reference column, not the forecast column.
Winners, losers, and the ones who decide
Energy wins, by a wide margin. Its profits are expected to roughly double compared with the same period a year earlier. The reason is plain: crude oil rose about 50 percent since the end of June and trades above 100 dollars a barrel. Some refiners saw profit forecasts nearly double inside three months. That is commodity math, not management genius.
Information technology is expected to grow profits about 63 percent. Strip out semiconductors and that collapses to roughly 24 percent. The sector is not uniformly strong; one slice is carrying the number. Communication services also grows fast, and two companies, Meta among them, explain much of it.
On the losing side sit materials, consumer staples and healthcare, all of which have seen forecasts trimmed. Inside a single national index, industries are diverging sharply. The tape echoes that split: NVIDIA near its high, KWEB bid, the DAX pinned near its low, gold soft.
Then there is AI, the word itself. In the April-to-June earnings calls, about two out of three companies used it, nearly double the five-year average. Companies that said it saw their shares rise about 16 percent since the start of the year; companies that did not saw about 8 percent. That is not proof that a word moves a price—many of those firms were already earning money from AI. Even so, the theme has escaped the boundaries of its own industry, and that is the durable observation.
What we watch, and what we cannot know
FactSet reports analysts expect full-year 2026 profit growth of about 32 percent. For 2027 those analysts expect about 15 percent. The second quarter of 2027 is pencilled in at 1.5 percent, essentially flat. That sounds like a slowdown, but a high base flatters nothing.
Two risks sit on top of that. Oil could fall, and energy profits would follow it down. AI momentum could falter, and semiconductors would follow. Neither is inside an analyst’s control. Both feed directly into the 29 percent headline that nobody has banked yet.
What this actually documents
What the report records is a direction of revision. Forecasts are not photographs of the future; they are habits, and this quarter the habit flipped. That is what makes it news: not a number, but a change in which way the number bends. The tape says the same thing in a smaller frame—some names bid, some offered, the sum almost unmoved. Markets rarely announce what will happen. They mostly publish, minute by minute, how willing people are to change their minds. This week, on both the map and the tape, a few were willing, and most were not.
Source figures are FactSet forecasts as of September 18, 2026. Market measurements are as of September 21, 2026, 04:59 UTC.
Sources
Mentioned organisations (context, not sources)
- NVIDIA — Organisation (homepage)
- Apple — Organisation (homepage)
- Microsoft — Organisation (homepage)
- Tesla — Organisation (homepage)