UK State Pension Triple Lock Tide May Turn
Meta commentary - no external expert source; basis: Feeds.bbci.co.uk (2026-09-28). #MetaEconPol
The Ebb
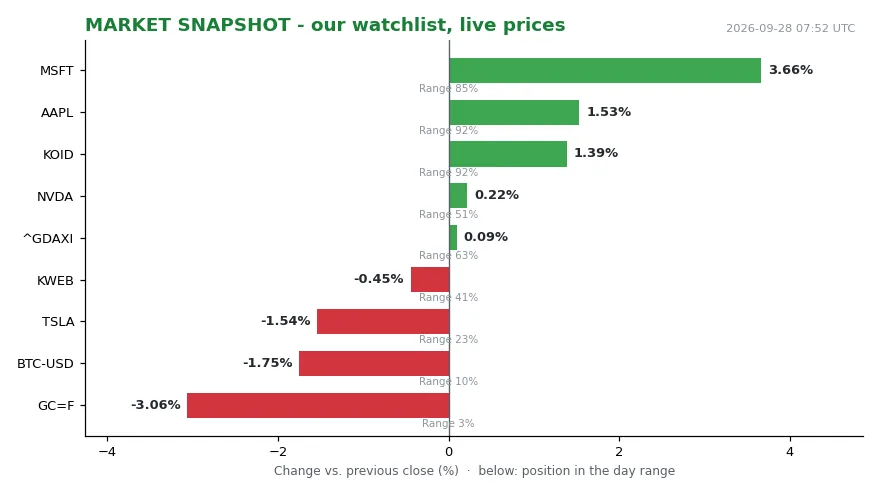
Microsoft trades at 516.17, up 3.66 % and pressed near the top of its range at 85 %. Apple sits at 341.07, up 1.53 %, at 92 % of range — where the current price sits between the day’s low (0 %) and high (100 %). Nvidia prints 225.07, up 0.22 %, mid-range at 51 %. Then come the hedges, and the hedges are bleeding. Gold is at 4188.80, down 3.06 %, pinned to 0 % of range — the lowest tick of the session. Bitcoin trades at 82910.00, down 1.83 %, near day lows at 7 % of range. Tesla is at 372.11, down 1.54 %, at 23 % of range, while the DAX sits close to flat at 25416.68, up 0.03 %, mid-range at 33 %.
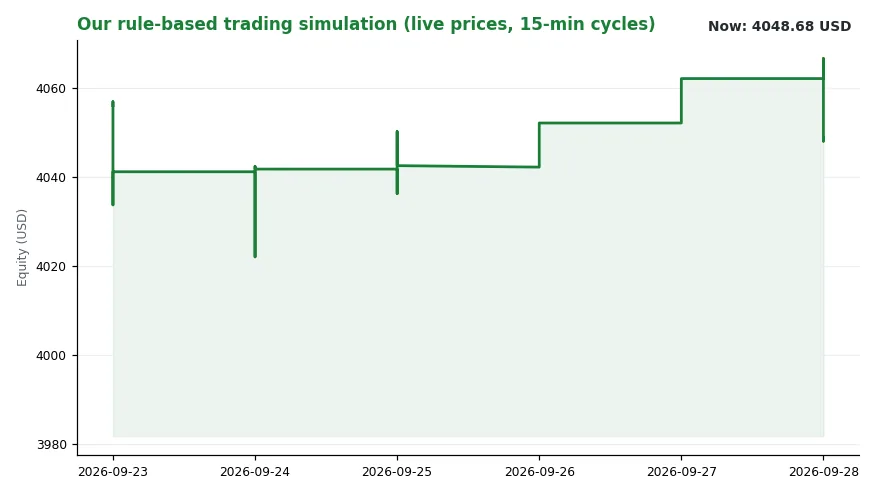
This is not a broad advance. It is capital leaving the instruments people buy when they are nervous and arriving in the biggest, most liquid quality names. Our regime reading — our internal signal that summarises the direction and strength of the market’s current state — compresses the same observation into one line: trend=falling, level=3.63. Sim equity — the value of our simulated, hypothetical portfolio, not real money — stands at 4049.32 USD, -0.31 % versus the same time yesterday, with 1448.12 in cash. The most recent logged decision was WATCH KWEB at 0.00. The busiest channel in our signal layer on 2026-09-27 was “central banks”, with 2 events.
The last April in which Britain’s state pension rose by the full triple lock — the UK rule that the state pension rises each April by the highest of inflation, average earnings, or 2.5 % — may be the last one anyone treats as routine, and the awkward part is that nobody can date it in advance. The policy, in theory, expires at the end of this Parliament. Every April, it delivers a rise of at least 2.5 %, or the highest of prices or earnings. For 16 years it has been the closest thing British politics has to a tide table: predictable, annual, and assumed to be a fact of nature rather than a decision.
The Flood
One force is inflation, the other is earnings. The lock simply takes whichever is running higher, with a floor of 2.5 % underneath both. In calm years the floor governs and the cost is modest. In turbulent years the highest of the three wins, and that is when the arithmetic starts to bite.
That is exactly what has happened. The lock is now costing GBP 15.5bn a year — treble the original estimates of its 2030 cost — largely because prices and earnings have been volatile. [1] Reverting to a simple earnings link — indexing pensions to the growth of average wages instead of to the triple lock — could save tens of billions of pounds a year over the long run. Those are the numbers that turn a welfare question into a fiscal one.
The channel from there to markets is not mysterious. A government that credibly commits to lower long-run pension outlays needs to borrow less, or at least to convince buyers of its debt that it will borrow less later. The UK, specifically, is seen as a place where successive governments have shirked tough long-term decisions. In a tricky moment for bond markets across all heavily indebted nations, a signal that Britain will take one is worth something.
That is why the wording mattered so much. The precise question about changing the lock in the next Parliament was put to the government, and the answer was that “the PM has said, like I have, that we must bring down welfare costs.” It was a non-denial. Non-denials are how policy shifts announce themselves before anyone is ready to announce them.
The Turn
Andy
Burnham will put forward tough decisions to fund a new national care service as part of Labour’s next general election manifesto, seeking a mandate to make the changes in the next Parliament. That framing matters. A mandate sought before a decision is a different political object from a decision imposed after one.
Reform’s leaders see the policy as a key potential dividing line with Labour, which raises the cost of touching it. Many in Westminster privately agree that the Osborne-era policy is unsustainable economically, and in the same breath argue it is politically impossible to unpick. That combination — unsustainable as it stands, politically untouchable — is what has kept the tide coming in for 16 years.
Pension campaigners make the counter-case with a fact that is easy to forget. Even after repeated increases, the UK’s state pension is not generous by international standards, though other countries run very different systems and very different rates of private provision. Comparing headline replacement rates — the share of a worker’s pre-retirement income that a pension replaces — across borders is a trap, but the direction of the complaint is real.
Former ministers point to the one argument that could move the politics: a quid pro quo. If the cash saved from the pension line is redeployed into an in-kind care service — care delivered as a service (hours, places) rather than as cash — the public is not simply being asked to accept less. It is being offered something it can see — care, in kind, rather than a number in an account.
Slack Water
The manifesto language, first, because “tough decisions” is a phrase that can mean almost anything until it is attached to a rate. Then the mandate question: whether a party asks voters for permission to change the formula in the next Parliament, or quietly lets the current arrangement lapse. Then the gilt market — the market for UK government bonds, i.e. the debt the government issues to borrow — will render its own verdict faster than any commentator.
A saving that has not been banked cannot be measured, and a mandate that has not been sought cannot be priced.
The triple lock is a promise about prices and earnings that nobody can forecast, written to pay out on whichever of them misbehaves most. Its cost is unknowable by design, and so is the cost of ending it. The tide will come in one more April, and then the question is whether anyone still has a tide table.
Sources
1. MSN (Original laut Text: BBC) — Portal copy
Mentioned organisations (context, not sources)
- Microsoft — Organisation (homepage)
- Apple — Organisation (homepage)
- Nvidia — Organisation (homepage)
- Tesla — Organisation (homepage)
- Parliament — Organisation (homepage)
- BBC News — Organisation (homepage)