UK Innovation Nation Plan to Turn Research Into Growth
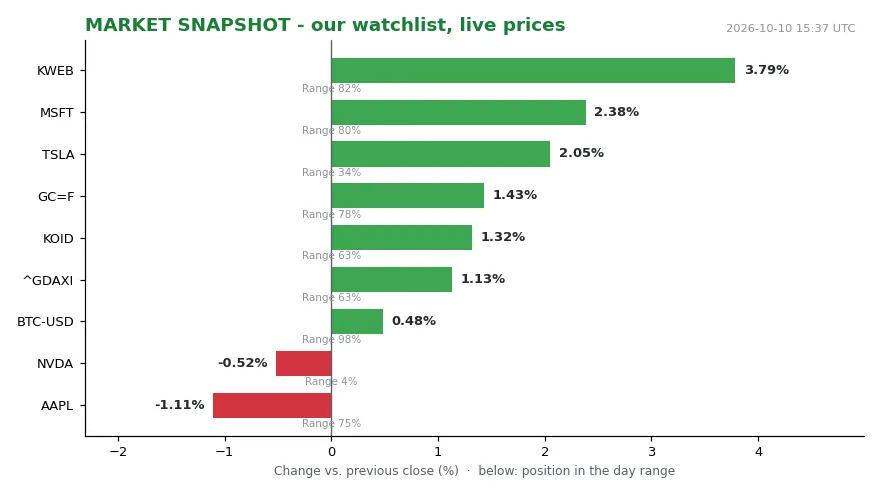
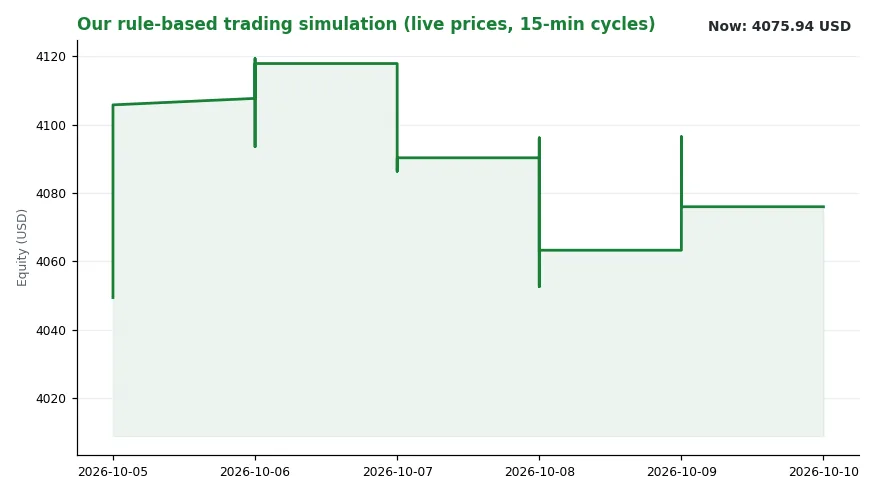
Gold prints 4,216.30 dollars an ounce, up 1.43% versus the previous close, at 78% of its daily range. Bitcoin prints 82,920.75, up 0.44% versus the previous close, at 91% of range — the strongest position on our board. Microsoft prints 535.07, up 2.38% versus the previous close, at 80% of range. Nvidia prints 229.28, down 0.52% versus the previous close, and it is the outlier: 4% of range, pressed to the floor. Apple sits at 336.64, down 1.11% versus the previous close, yet still at 75% of range. Tesla trades at 382.70, up 2.05% versus the previous close, mid-range at 34%. KWEB leads everything, up 3.79% versus the previous close to 24.93, at 82% of range. The DAX adds 1.13% versus the previous close to 25,087.27, mid-range at 63%. KOID is up 1.32% to 35.42, also mid-range at 63%. Our simulated book stands at 4,075.94 dollars, unchanged from the same time yesterday, with 2,049.10 in cash; the busiest signal channel today is central banks, with two events.
The shape, not the level, is what matters. The strongest positions cluster in gold, bitcoin, Microsoft and KWEB. In our reading, the weakest sits under the name that has led this theme. That is rotation inside an innovation complex, not flight from it. Money is leaving one seat and taking four others. Our instruments cannot say who is moving. They can say the money did not leave the room.
The conference that frames this argument meets in Manchester [1]. The city is where the first Industrial Revolution began, and the question it now poses is whether British hands keep hold of the next machine — or build it and watch someone else own it The news itself is concrete. The Innovation Nation Conference in Manchester, addressed by the prime minister, Andy Burnham, hears the case that the coming decade is almost certain to bring the greatest scientific breakthroughs in a century [1]. The claimed territory is wide: AI, quantum computing and biology aimed at cancer, at treating or preventing dementia, at the growing resistance to antibiotics [1]; energy that is sustainable and an environment protected at the same time; and AI in education, health and social care, and in modern manufacturing [1]. The US and China are named as the obvious innovation powerhouses. Britain is not. [1] What Britain has is a research base that punches far above its weight [1]. It is home to four of the world’s top 10 universities and 16 of the top 100, five of which rank in Europe’s top 10 for spin-outs — companies built on intellectual property produced by university research [1]. With less than 1% of the world’s population, the UK produces 6% of research papers, nearly 9% of citations and 12% of the most highly cited research [1]. That is the asset side of the ledger.
The recent record backs it up: AlphaFold predicts how proteins behave, viral-vector vaccine technology came out of the same ecosystem, and AI detects cancer as reliably as radiologists [1]. Britain already sits at the intersection of AI, quantum computing and synthetic biology [1]. “The question then is: why, having led the first Industrial Revolution, should the UK not be the world’s great innovation nation once again?” [1] Two poll numbers set up the political problem. Polling for the conference finds that 75% of people agree innovation is essential for creating UK economic growth [1]. Only 36% of the British public believes the country is a world leader in science [1]. The public backs the goal and doubts the standing. In our reading, that gap is what the government’s 10-year plan is meant to close.
The channel: intensity into income
The mechanism on offer is arithmetic. Raise Britain to Swedish or Japanese levels of innovation intensity and, over time, every household would be £5,000 better off — the author’s own calculation, not an independent forecast [1]. National income would rise by £150bn a year as research and development spending feeds through into productivity [1]. A jobs plan on the scale that Our Scottish Future has proposed for Scotland would mean about 3m new jobs across the UK [1]. They are a scenario, not a forecast.
The bottlenecks are named just as plainly. Britain is good at startups and spin-outs and slow at turning startups into scale-ups [1]. It is slower still at turning scale-ups into global success stories [1]. Per head of population, the US has double the number of $1bn companies and nearly three times as many $10bn-plus companies as the UK [1]. And when UK firms do scale at home, three-quarters of venture capital investment comes from overseas [1]. That last figure deserves emphasis. The upside of a British success is, more often than not, financed abroad.
The proposed levers are specific: capital access for growing firms, including from UK investors; new incentives for investors; public-private partnerships on the German, French and Italian model, capitalised by the British Business Bank and the national wealth fund [1]; competition policy that favours new entrants against vested interests, aligned with R&D credits that work for companies of every size [1]. Research for the conference identifies 127 innovative clusters covering every region and nation of the UK [1]. Each needs long-term support for infrastructure, skills training and backing from UK Research and Innovation [1]. Power then has to move: mayors and regional authorities need room to act locally while keeping access to global markets [1].
Who wins, who loses, who decides
Winners are the spin-out founders and the university offices that produce them, the 127 clusters, and the regional mayors who gain authority [1].
Incumbents sheltered by vested interests lose when competition policy tilts toward new entrants [1]. The British saver loses when the growth stage of a domestic company is financed from abroad, because the household does not hold the upside. And the 64% who do not see Britain as a science leader lose a story they could tell about themselves [1].
The deciders are the government preparing the 10-year plan, UK Research and Innovation, the British Business Bank, the national wealth fund, and devolved mayors and regional authorities [1]. The conference is a device for forcing decisions, not a decision.
Britain does not lack genius or great assets [1]. What it has not done is find its “lost Einsteins” — young people in lower-income areas who have the talent but not yet the opportunity to show it [1]. That is a distribution claim, not a sentiment. It locates the constraint at the starting line, not in the supply of ability.
What to watch
Three things are observable from here. First, the 10-year plan: does innovation move to its centre, or stay a chapter? Second, the capital stack: does the overseas share of venture investment begin to fall? Third, the 127 clusters: do they become a list of places that received money, or of places that produced companies?
Our tape adds a fourth. A rotation that lifts gold, bitcoin, Microsoft and KWEB together is a market pricing several futures at once. It is not a verdict on any national strategy. Gold at 78% of range and bitcoin at 91% of range are the tell: some of the money funding the next decade wants insurance attached.
Honesty requires caveats. The £5,000 and £150bn figures are one author’s calculations, not an independent forecast [1]. Polling measures belief, not behaviour. Cluster counts measure potential, not output [1]. And our snapshot is nine instruments taken at 15:32 UTC on 10 October 2026, one minute after the quotes were fetched — a watchlist, not the market.
Sixty-four years before the conference, John F Kennedy declared that the US would lead a nationwide effort to be first on the moon [1]. The moon was not his first choice: he wanted a project everyone could feel part of, and would have preferred one on Earth if he could have found one with the same power to inspire [1]. “This generation does not intend to founder in the backwash of the coming age,” he said of his own country [1]. The argument in Manchester is that this generation of Britons has no intention of being left behind as the age of AI accelerates.
What the case finally reveals is a theory of how a country keeps what it makes. Invention is the cheapest part. Investment, manufacturing and ownership are where decades get decided: “We must invest in it, manufacture it and, wherever possible, own it here in Britain” [1]. Ownership, unlike invention, cannot be gifted or borrowed — and that, rather than any single breakthrough, is what the next ten years will test. [1] Gordon Brown, commentisfree, The Guardian, 9 October 2026. Our own market measurement, watchlist quotes fetched at 15:32 UTC, 10 October 2026. Educational analysis, not investment advice.