Social Security 2027 COLA Trumpflation and Medicare Premiums
Market tape
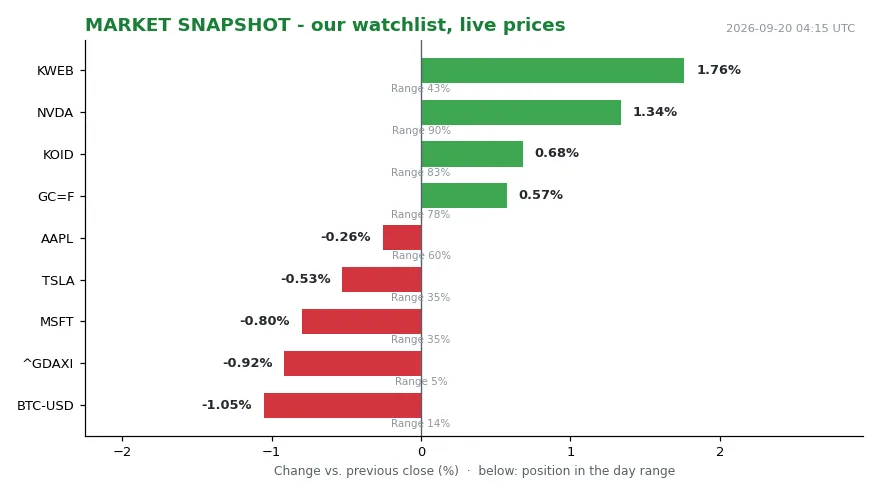
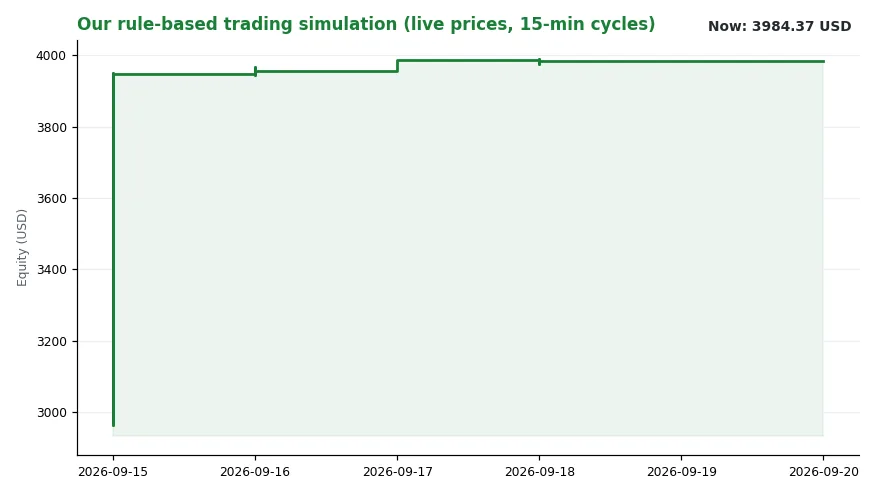
The tape at 04:09 UTC on September 20, 2026 shows a market that is repositioning rather than retreating. NVDA printed 222.27, up 1.34 percent, near the top of its daily price range. Gold futures traded 4,424.90, up 0.57 percent, also near its daily high. Bitcoin fell 1.00 percent to 80,414.23, near its daily low. The DAX closed at 25,304.06, down 0.92 percent, near its daily low. The DAX sits at the bottom of its range, not at a support level. KWEB added 1.76 percent to 24.83, in the middle of its daily range. The rule-based simulation account holds 3,984.37 USD, flat versus the same hour a day earlier. Cash sits at 2,002.35 USD. The last logged action was an observation on KWEB. The reason logged was that the market was closed.
The pattern matters more than the individual prices. Gold is rising. Crypto is falling. Europe is soft. China internet is quietly firm. The attention signals show where attention sits: the busiest channel on September 19 was the central bank channel, with one event logged. The market reading is trend falling, level 3.63. That is money moving toward safer assets. Money is not leaving the field.
That is the backdrop for a US policy item with global market relevance. Tens of millions of Americans feel it every January.
The annual COLA notice is a single percentage that decides whether a household budget holds, and it sits as a line item in the largest retirement system on earth.
On October 14, the U.S. Bureau of Labor Statistics publishes the September inflation report. [1] That release is the final input. It completes the calculation of Social Security’s 2027 cost-of-living adjustment, or COLA. More than 71 million traditional beneficiaries are waiting on it. The count includes retired workers, workers with disabilities, and survivors of deceased workers.
COLA mechanism
The mechanism is statutory and dates to 1975. In 1975, the Consumer Price Index for Urban Wage Earners and Clerical Workers became the yardstick. [1] Since then, raises have arrived in every year but three. Those three were 2010, 2011 and 2016. The COLA is a formula fed by price data, not a discretionary payment and not a negotiation.
This year the formula is being fed something unusual: policy-driven price pressure. Two of President Donald Trump’s policies are pushing prices higher. Two channels matter.
The first is tariffs. In April 2025, the administration imposed sweeping global tariffs and higher retaliatory tariffs on dozens of countries. [5] The U.S. Supreme Court invalidated those tariffs in February 2026. [4] They still lifted consumer prices through 2025. That lift modestly boosted the 2026 COLA. In July, the administration announced new global tariffs on more than 80 countries. [5] The range runs from 10 % to 12.5 %. [5] A different legal justification was used. Duties on imports raise domestic production costs and feed through to consumer prices.
The second channel is energy, and it is bigger. The Iran war closed the Strait of Hormuz, and fuel prices soared. The effects are no longer confined to the pump. They are appearing across the broader economy.
Analysts have a name for the result: Trumpflation, meaning inflation driven specifically by the president’s policies. For retirees, the consequence is arithmetic. Above-average inflation produces an above-average raise.
Two forecasters agree on the size. The Senior Citizens League is a nonpartisan senior advocacy group. [3] Mary Johnson is an independent Social Security and Medicare policy analyst. [6] Both project a 3.5 percent increase in payouts next year. [6]
Johnson’s work is translation: from a price index to a household budget. That translation passes through Medicare.
Medicare netting
Close to half of Social Security’s age 65-and-up population is enrolled in traditional Medicare. Part A covers hospital stays, Part B covers outpatient services, and Part D covers prescription drugs. Part A costs nothing for roughly 99 percent of retirees. Part B does not. Its standard monthly premium is $202.90 in 2026.
Here the arithmetic turns. Throughout this century, the Part B premium has climbed faster than the COLA. Beneficiaries received raises of 3.2 percent, 2.5 percent and 2.8 percent in 2024, 2025 and 2026. The premium rose 5.9 percent, 5.9 percent and 9.7 percent over the same years. When the premium outruns the raise, the net gain shrinks. It can vanish.
The 2026 Medicare Trustees Report forecasts a 3.25 percent premium increase next year. [6] Against a 3.5 percent COLA, beneficiaries would come out ahead. On a percentage basis, that has not happened since 2023. That is the silver lining. It is thin, and it is real.
The other side of the ledger is the trust fund.
Trustees outlook
The Social Security Board of Trustees has warned about long-term funding gaps for decades. Those warnings predate Trump’s two non-consecutive terms. Since 1985, the Trustees have projected a 75-year shortfall between income and outlays. Through 2100, that gap is estimated at $29.3 trillion. [2]
The nearer problem is the Old-Age and Survivors Insurance trust fund. Its asset reserves are projected to deplete in the fourth quarter of 2032. [2] This is not bankruptcy. The Old-Age and Survivors Insurance trust fund needs its reserves to keep paying full benefits. But if the reserves run dry, sweeping benefit cuts of roughly 22 percent may be necessary. [2]
The Trustees factor the annual COLA into their long-run models and assume modest yearly increases. A 3.5 percent raise is well above average.
The distribution of the gain is split. Beneficiaries receive higher dollar amounts. If the Medicare forecast holds, they keep a slice. Enrollees absorb a premium increase that eats into the gain. The Trustees publish the depletion date; they do not control it. The Bureau of Labor Statistics publishes the inflation number; it does not choose it. The White House sets tariffs. A war sets fuel prices.
Three dates matter from here. October 14 brings the September inflation report. The Medicare premium announcement turns the 3.25 percent forecast into a decision. The next Trustees Report shows whether the 2032 depletion date moves. One further uncertainty: the July tariffs may face a legal challenge, as the April ones did.
The rotation is visible on the screen. Gold sits near its highs, while Europe and bitcoin sit near their lows. The central bank channel was the busiest of the previous session. Markets, like the Trustees, are pricing a longer fight with inflation. The simulation stayed flat by choice, logging observation rather than action.
The 3.5 percent COLA and the roughly 22 percent benefit cut are both projections, published and open to revision, not predictions.
This is education and analysis only. It is not investment advice and not a recommendation to buy or sell any security.
Sources
1. U.S. Bureau of Labor Statistics — Organisation (homepage)
2. Social Security Board of Trustees — Organisation (homepage)
3. The Senior Citizens League — Organisation (homepage)
4. U.S. Supreme Court — Organisation (homepage)