Rent History Becomes Key to Zero Deposit Mortgages
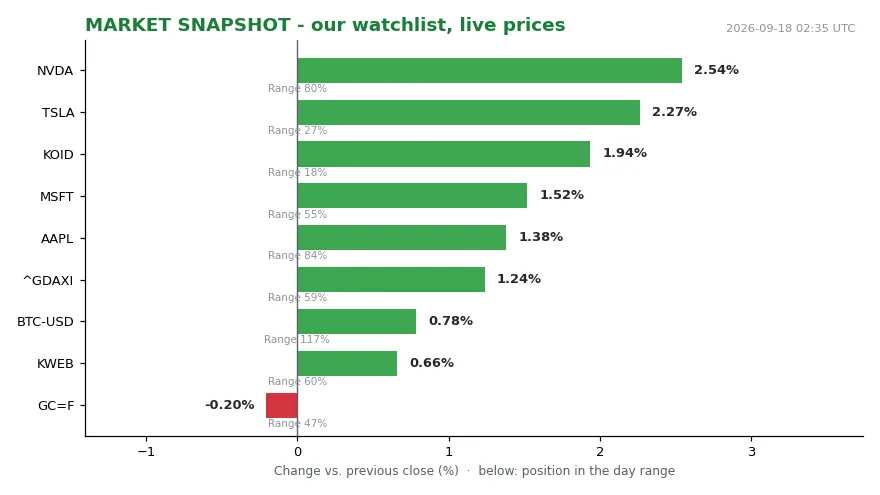
Risk appetite in the watchlist is concentrated at the top of the tape rather than spread across it. The latest measurement, taken at 2026-09-18 02:30 UTC, puts NVIDIA at 219.34, up 2.54 percent versus the previous close and sitting in the top 80 percent of its daily range. [1] Apple trades at 337.00, up 1.38 percent, and is even more stretched at 84 percent of its range. [2] Bitcoin prints 76862.60, up 0.67 percent, with a position within its daily range of 100 percent, meaning it is at the top of that range. Gold futures at 4388.00 are fractionally lower, down 0.27 percent and mid-range at 37 percent. The German DAX adds 1.24 percent to 25716.71 but stays mid-range at 59 percent. The fund is up 1.94 percent to 35.27 but sits near the day’s low, at 18 percent of range. Microsoft at 497.75, up 1.52 percent, and Tesla at 366.20, up 2.27 percent, sit at 55 percent and 27 percent of their ranges respectively. [3]
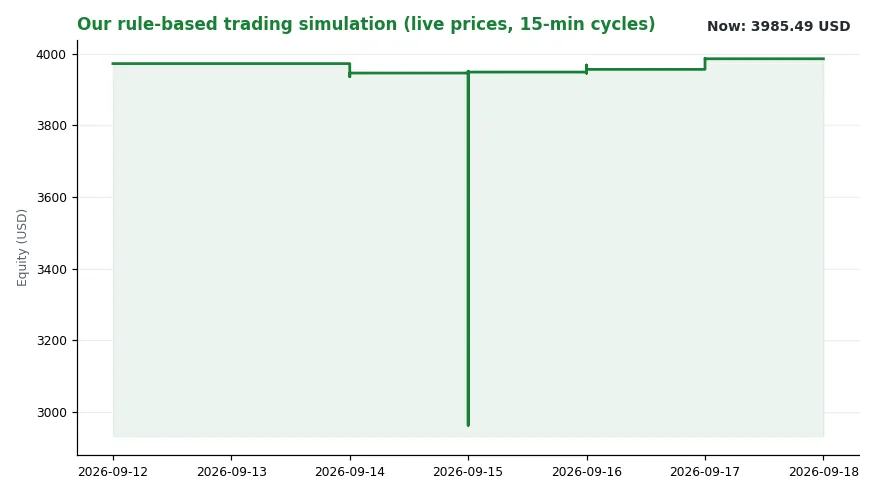
The pattern is narrow rather than broad. Liquidity is rotating into a handful of the largest companies by market value while other listed proxies mark time. The portfolio reflects that caution: the book stands at 3985.49 USD, effectively unchanged from the same time yesterday, with 1987.26 USD held in cash. The last logged decision was to watch the China internet ETF at 0.00 because the market was closed; the observation was recorded and no trade was invented. The most active signal source is “central bank” on 2026-09-17, with three events. The trend reading is falling, level 3.63.
Two statements appear to contradict each other, and both are true. First: British mortgage lending is getting riskier, because the share of new loans with deposits below 10 percent of the property’s value is the highest since 2008. [7] Second: the same market is getting more careful, because the gatekeeping behind those loans is tighter than at any point in that same period. The contradiction resolves once the location of exposure is examined.
The Deals Behind the Numbers
The story is about housing access rather than equity markets. Conroy, 32, and his partner Amber, 28, rented in central Manchester and could not save a deposit. They took Skipton Building Society’s Track Record mortgage, which covers 100 % of a property’s value with nothing paid upfront. In August they bought a four-bed house for £242,000 in Swinton, on the edge of Manchester. Their rate is 5.33 percent, fixed for five years, on a 25-year loan. [5] Monthly repayments are around £1,500 — roughly what they were paying in rent.
Bronya, 27, and her partner George, 29, took a different route to a similar place. Lloyds lent them £258,000, roughly 98 percent of the value of their four-bedroom house in Rhuddlan, North Wales, on a 33-year term. [6] They put down £5,000. Their rate is 5.89 percent, fixed for five years, and their monthly payment is about £1,400 — again close to the rent they had paid for a one-bedroom flat. They could have saved a larger deposit but chose to spend upward of £20,000 on a renovation instead.
Behind both cases sits a single structural fact. Bank of England data shows the average deposit for a first-time buyer is around 20 percent. [7] Saving that while paying market rent is the bottleneck, not the willingness to pay a mortgage. Lenders including Lloyds, Santander, Skipton and Yorkshire Building Society have answered with products covering 95 percent of value and above, and in some cases the full 100 %. [8]
How the Mechanism Works
The mechanism runs through three channels. The first is price: a small or zero deposit is compensated by a higher interest rate, so the cost of entry is paid monthly instead of upfront. The second is eligibility: Skipton requires borrowers to show at least 12 consecutive months of rent payments and six months of credit payments. [5] Lloyds will not write its £5,000-deposit product on new-build or shared-ownership homes. [6] The third is regulation: after a recent rule change, lenders can offer more “flex” on how much someone borrows, provided it stays within their means.
The risk most often named is negative equity. That is when the property is worth less than the loan still outstanding. It only becomes expensive if the borrower is forced to sell. Conroy says he is aware of it and plans to pay more than the required mortgage instalment for the first five years to build equity faster. He describes the property market as always carrying an element of a gamble, and says he researched the area before buying. George’s answer is time: “We plan to stay here our whole lives.” [6]
Who wins, who loses
The distribution of gain and loss is straightforward. Lenders win on margin, because a higher rate on a 98 or 100 % loan is compensation for risk that is priced rather than avoided. Borrowers win on access, because they own instead of rent at a similar monthly outlay. The losers are borrowers who hit negative equity and need to move, and anyone whose rent history fails the eligibility test. The 2008 comparison is why this argument exists at all. Widespread uptake of low-deposit lending by people who could not afford it was a major factor in the global financial crisis.
David Hollingworth of brokers L&C Mortgages argues the current products are not the same animal. [10] He points to the affordability checks and to lenders recognising people with “good affordability” who still cannot save while renting. [10] His caution is the least glamorous part of the story: borrowers should check what the monthly payment looks like and ask whether rates could rise. [10] That second question matters more than the first, because 5.33 and 5.89 percent are fixed for five years, not forever. The reset date is the real cliff edge.
What to watch next
The next signals to watch are as follows. First, whether the sub-10 percent deposit share keeps climbing from its post-2008 high, or plateaus as lenders ration these products. Second, the five-year fix expiries, where today’s borrowers will meet whatever rates then exist. Third, local price data in places like Swinton and Rhuddlan, because negative equity is a local phenomenon, not a national one. Fourth, the macro channel monitor, where “central bank” was the busiest signal source on 2026-09-17, since rate expectations remain the transmission belt. It is not known how any of this breaks. The Bank of England’s series and the lenders’ own eligibility rules will show the answer before the commentary does.
The cheapest, simplest version of this technology is already on the shelf. It does not require a deposit at all: Skipton’s Track Record product asks for 100 % financing and substitutes a documented rent history for cash. [5] On the Lloyds side, £5,000 against a £258,000 loan is under 2 percent of the purchase price. The gate has moved. What used to be a savings problem is now an underwriting problem. The price of admission is a rate in the mid fives, fixed for five years, with everything after that left open.
Sources
1. NVIDIA
2. Apple
3. Microsoft
4. Tesla
6. Lloyds
8. Santander
10. L&C Mortgages