LV Subsidence Claim Shows Risk Refusing to Be Priced
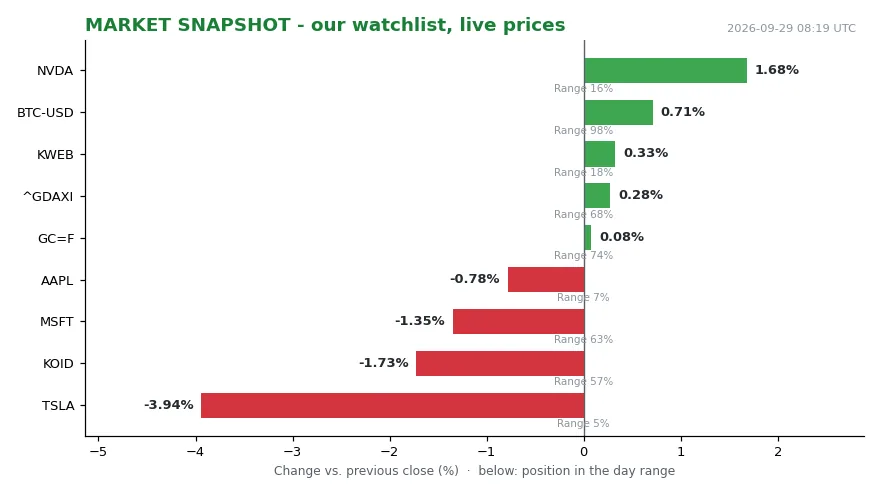
Monday’s tape splits, and our own measurements show the seam. NVDA prints 228.86, up 1.68 % versus the prior close, yet it sits near the day’s lows at only 16 % of its range — strength that cannot hold its own ground. TSLA trades at 357.45, down 3.94 %, pinned at 5 % of range. BTC-USD changes hands at 84,032.96, up 0.65 %, near the day’s highs at 94 % of its range. GC=F, gold, stands at 4,174.40, up 0.14 %, at 82 % of range. The pattern is a rotation, not a panic.
The rest of the watchlist agrees. AAPL is quoted at 338.40, down 0.78 %, at 7 % of range. MSFT sits at 509.22, down 1.35 %, mid-range at 63 %. ^GDAXI holds 25,425.75, up 0.20 %, at 56 %. KOID trades 35.88, down 1.73 %, at 57 %. KWEB is at 24.66, up 0.33 %, but only at 18 % of range. Equity exposure in NVDA, TSLA, AAPL and KWEB is being parked at the bottom of its daily band, while two hedges — crypto and bullion — sit near the top of theirs.
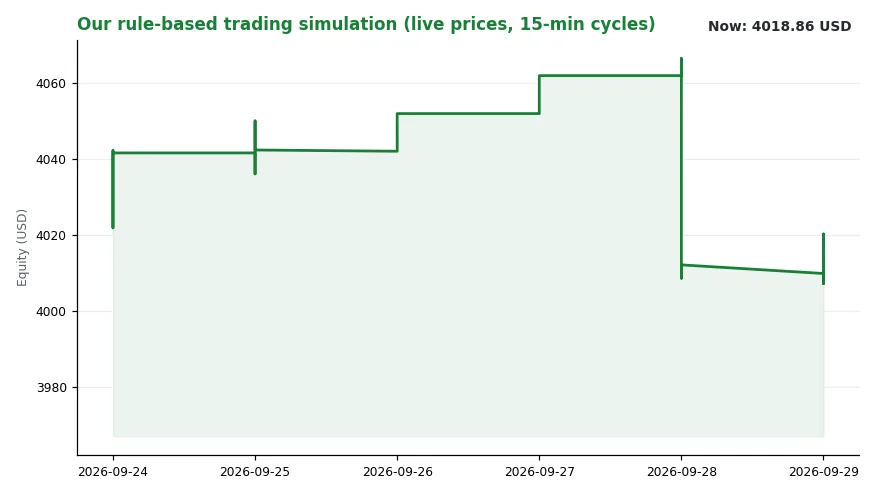
Our regime reading: trend=falling, level=3.63. The simulated equity book stands at 4,018.86 USD, up 0.16 % against the same time yesterday, with cash of 1,210.27. The latest rule-based decision was WATCH KWEB @ 0.00, logged at 10:09:57. The busiest signal channel on 2026-09-28 was ‘central banks’, with 2 events.
Read together, those figures describe a market repricing risk.
The claim file
On 29 September 2026 at 08.00 CEST, the Guardian’s Consumer Champions column, written by Anna Tims and last modified at 09.54 CEST, published a household’s account of a subsidence claim that has not been settled.
The family — with three young children — lodged a subsidence claim in 2023 for damage to an extension and a conservatory. The household states that LV= General Insurance did not authorise the repairs that independent experts had recommended. Instead, the household says the insurer spent years stalling and proposing inadequate, superficial patching methods. Three years on, significant cracking in the interior walls caused a radiator to shear away. The household says it supplied proof to LV=, which was ignored while the property deteriorated.
The price side also matters. The household’s annual premium rose from GBP 400 to GBP 2,500. An independent surveyor, commissioned in May after an impasse, concluded that the damaged extension needed underpinning or rebuilding. LV= states that it obtained a quote for underpinning last February, but that the work was not carried out. The insurer has acknowledged that the cracks have worsened and that a full rebuild is now required. It says repairs will begin as soon as the designs and the council bureaucracy are complete, and it attributes both the subsidence and the delay to a eucalyptus tree owned by a neighbour who refuses to remove it.
Two quotations
[1] An LV= spokesperson: “LV= General Insurance takes this claim extremely seriously and we understand and appreciate the frustration at the time it has taken to resolve it. [1] Subsidence claims can be protracted because the most important step is to address the cause of movement, in this case tree removal, before permanent repairs can be undertaken. [1]“
[2] The household, on the premium: “I feel they are penalising us for a claim. [1]“
LV= has also stated that it is reviewing the premium increase under its complaints procedure.
The mechanism
Insurance is the channel through which physical risk becomes a number. Subsidence claims are soaring as repeated droughts cause soil to shrink, and nearby trees accelerate the problem. Several trees were removed on LV=‘s advice, but this did not resolve the movement.
This is where the mechanism becomes visible rather than theoretical. A claim file is not a frozen object. While it sits, the loss keeps accruing. In this case, what the surveyor framed as underpinning or rebuilding in May has since been reclassified by the insurer itself as a full rebuild. The liability does not wait for the paperwork, and it does not shrink when the remediation of the root cause — here, tree removal — remains unresolved.
Premium repricing is the second half of the same channel. When expected loss costs rise across a book, the carrier passes them back to policyholders. The household’s increase from GBP 400 to GBP 2,500 is one data point in that transmission, and it is now under internal review.
The actors
The household carries the physical cost: a family with three young children in a property the household describes as collapsing around them. LV= holds the decision rights over authorisation, sequencing and repair scope. The neighbour controls the root cause, on the insurer’s own attribution, and has declined to remove the tree. The independent surveyor supplied the technical evidence that reframed the job. The council sits in the permitting chain that LV= cites as a remaining dependency.
Through the price channel, other policyholders in drought-exposed areas are price takers, not decision-makers.
The trade-offs are real and they cut both ways. Buying time on a claim can protect a loss ratio in one reporting period. Deferring root-cause work converts a smaller repair into a larger one, as this file appears to show. Raising a premium preserves the economics of a policy. It also tests whether the customer stays at all.
What we watch next
Four things, and none of them is a forecast. First, whether LV= actually begins the rebuild it has now acknowledged is required. Second, the outcome of the complaints review of the premium increase, which is unresolved. Third, whether the neighbour’s eucalyptus is removed, since the insurer’s own account makes that the precondition for permanent repairs. Fourth, whether the drought cycle keeps pushing subsidence volumes higher, which would make this file a template rather than an exception.
We publish measurements and mechanisms, not recommendations.
If the deferral continues, the arithmetic is unkind: the house keeps moving while the file stays open, and the loss keeps compounding while the premium is already repriced. That is the risk this file shows refusing to be priced.
Sources
1. Guardian — Quote source (original article)