Greggs Plans 740 Job Cuts While Sales Grow: The Cost Arithmetic Behind the Sau
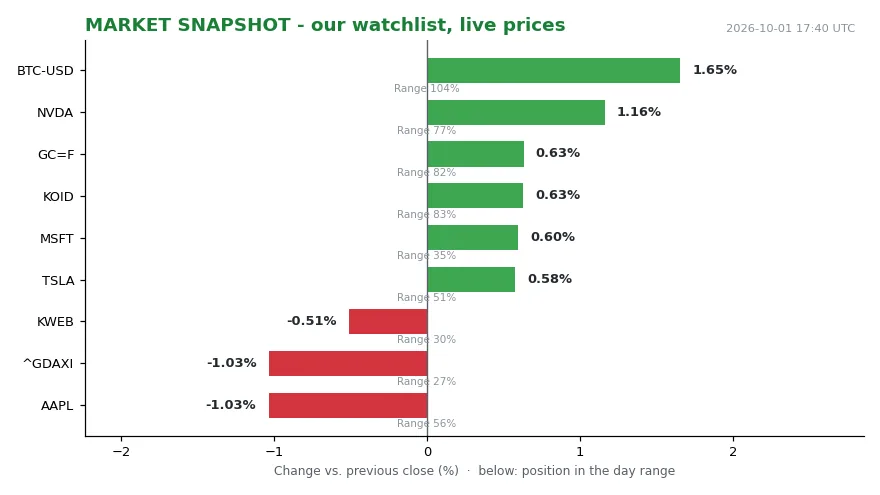
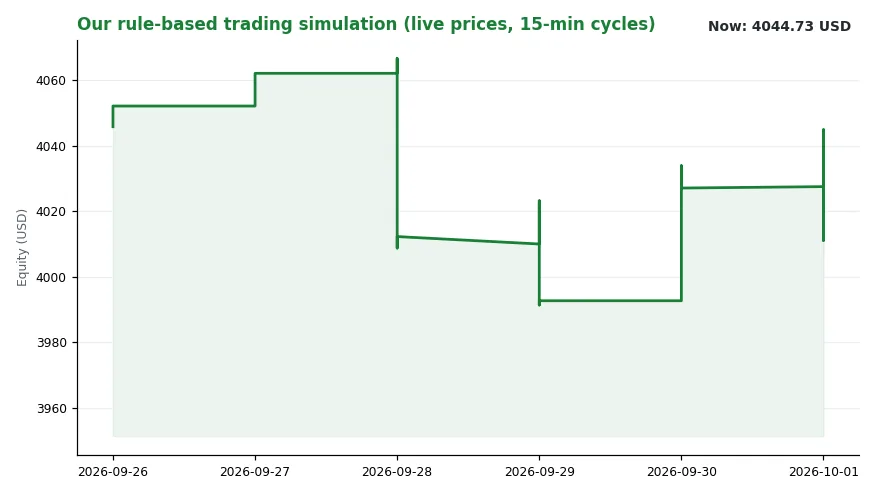
sage Roll At 17:37 UTC on 1 October 2026, our quote sheet showed a market unwilling to commit to a direction. NVDA traded at 230.87, up 1.09% against the previous close, sitting at 72% of its daily range. BTC-USD printed 84,777.79, up 1.45%, at 94% of range — near the day’s high. KOID stood at 35.99, up 0.74%, at 90% of range. Gold futures (GC=F) held 4,206.80, up 0.48%, at 70% of range. The DAX, by contrast, sat at 24,939.35, down 1.03%, at 27% of range. KWEB eased to 24.41, down 0.43%, mid-range at 33%. Our simulated equity book read 4,044.73 USD, up 0.44% versus the same time yesterday, with 2,020.64 USD in cash. The signal layer logged ‘central banks’ as the busiest channel on 30 September, with two events. The regime reading: trend=falling, level=3.63. Taken together, those figures describe rotation, not conviction. Risk appetite is being spent selectively. Europe softens, crypto pushes toward its highs, and the middle of the board drifts. That is the weather in which a British bakery chain made a decision about factories.
What was announced
The news is simple and awkward at once (1). Greggs has announced plans to close four UK factories. The company says the move could cost 740 jobs over the next two and a half years. [1] The sites in question are Enfield in north London, Penrith in Cumbria, Kelso in Roxburghshire, and Seaham in County Durham (1). Distribution operations would continue from Enfield. Manufacturing at the Treforest site in Wales could also be affected, though Treforest would keep operating as a distribution centre (1).
The financial framing matters more than the map. Including disruption costs and redundancy payments, the closures would initially cost £60m. By 2028, the company projects savings of £20m each year (1). Our own arithmetic on those two figures gives a payback period of roughly three years, before any discounting. That is the expectation baked into the plan: spend once, save annually, grow afterwards.
Why does this move anyone? Because a growing company cutting jobs breaks the usual story. Greggs is not a distress case. It is the UK’s biggest fast-food business, built on low-cost pastries, cakes and hot drinks (1). Sales growth in the most recent quarter was 7.7%, up from 7.2% in the first half of the year. This year the chain has opened 57 net new shops. It plans between 100 and 110 openings by the end of 2026.
The mechanism
The channel here is cost structure, not demand. A retailer that adds shops faster than it adds profitable volume ends up with a fixed asset base sized for a different company. Factories are the least flexible part of that base. So the lever becomes footprint: four sites, 740 roles, £60m of one-off cost, £20m a year thereafter.
A second channel runs through prices. The company has been pushing price through its menu, and the source does not quantify the individual increases. That is pass-through, and pass-through has limits.
A third channel is forward inflation. Greggs told investors that stronger sales had “modestly improved” its outlook for this year (1). It also flagged that “there are signs of greater inflationary pressures in 2027” (1). That sentence is the hinge between the two stories. Our own signal layer put ‘central banks’ at the top of the channel list on 30 September. Greggs is making at company level the same observation macro desks are making at index level. Costs are expected to keep pressing into 2027. So the cost base is being rebuilt now rather than later.
Who wins, who loses, who decides
Start with the 740. They are the people inside the word “could”. The company’s own commitment is narrow and careful (1): “Our immediate priority is to minimise the impact on our people where possible. We will enter into a consultation period shortly to work with trade unions and employee representatives of those affected to refine and develop these proposals.” [1] Refinement cuts both ways. Proposals can shrink, and they can also shift. Treforest is the clearest illustration: manufacturing affected, distribution retained. One site, two outcomes, two groups of workers.
Then come the communities. Factory work in Enfield behaves differently from factory work in Penrith, Kelso or Seaham. Then come the shareholders. The market read the plan as discipline rather than damage.
Then come the customers, who ultimately decide whether the arithmetic closes. Iced matcha lattes, a wider salad range and chicken rolls helped lift summer sales (1). But the loyalty test sits lower down the menu. Freetrade analyst Alex Pugh framed the risk on the sausage roll, noting it had survived a heatwave and a cost of living crisis and that a higher price could test customer loyalty”. [1] And who decides? Management decides the footprint. The consultation decides the details. The customer decides the volume that has to carry the remaining fixed costs. Scale buys negotiating room. It does not remove the trade-off.
What we watch next
Four things are checkable. First, the consultation outcome: timelines, redeployment numbers, and whether all four sites close exactly as proposed. Second, the 2028 savings figure, which is a projection rather than a receipt. Third, the store programme — between 100 and 110 openings by the end of 2026 is a large number set against 57 net openings so far this year. If openings slow, the savings case changes shape. Fourth, the 2027 inflation commentary, where pricing power gets tested.
Three caveats apply. The consultation may alter the proposals. The £60m includes disruption costs, which are hard to forecast. And the sales trend underpinning the whole plan is one quarter old.
The shape is familiar. A profitable company cutting hundreds of jobs is a familiar pattern. This case differs in one specific way. The cut is not a response to falling sales. Sales are rising. The cut is a response to the cost of the next three years. That is a colder calculation, and a harder one to argue with. It also explains why the shares went up. The pricing risk is not the risk these numbers describe. The number that matters is 740. Behind it sits a company that has decided to spend £60m now in order to save £20m a year later.
Sources: (1) Guardian, BBC, MSN, 30 September 2026; market figures from our own measurement, 1 October 2026, 17:37 UTC. Educational analysis only — not investment advice.