Gold at the Low, Nvidia at the Top: The Quiet Session Before the Headlines
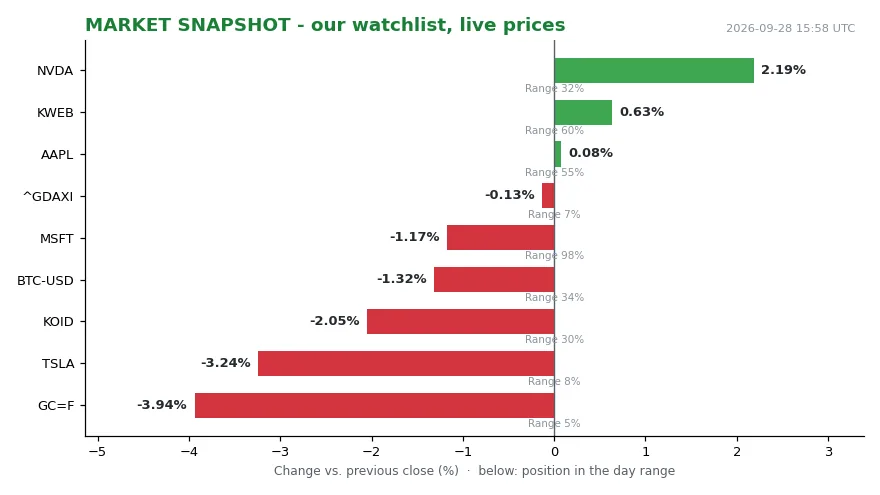
At 15:57 UTC on 2026-09-28, our watchlist printed NVDA at 229.94, up 2.17% against the previous close and sitting mid-range at 31% of the day’s band. TSLA traded at 360.39, down 3.15%, near its low with only 11% of the range behind it. Gold — GC=F — stood at 4152.10, down 3.91%, at 5% of range, the weakest position anywhere on our board. AAPL was effectively unchanged at 341.24, +0.05%, mid-range at 52%. MSFT fell 1.16% to 510.18 yet still printed at 99% of its range, near the day’s high. Add ^GDAXI at 25374.42, -0.13%, at 7% of range; BTC-USD at 83331.23, -1.33%, mid-range at 33%; KWEB at 24.73, +0.63%, mid-range at 60%; and KOID at 35.67, -2.30%, at 9% of range.
Ten instruments, and not one of them agreed on a story. That is the measurement. Everything after this is commentary.
The silence is the loudest item in the file. No headline in our data explained a 3.91% drawdown in the asset that is supposed to price bad news. Meanwhile the source page we were reading is, by any reading, alarming.
Gold at Low Nvidia at Top Before Headlines
The cited Euronews report covers a different story entirely: the US and China have listed around $30bn worth of goods for possible tariff cuts, and the piece examines what that could mean for Europe. [1]
So here is the contradiction, stated plainly. If two of the world’s largest economies are moving toward tariff cuts, why is gold — the metal that is meant to price geopolitical stress — parked at 5% of its range, near the day’s low?
Work backwards through the evidence, because that is the only honest sequence available to us.
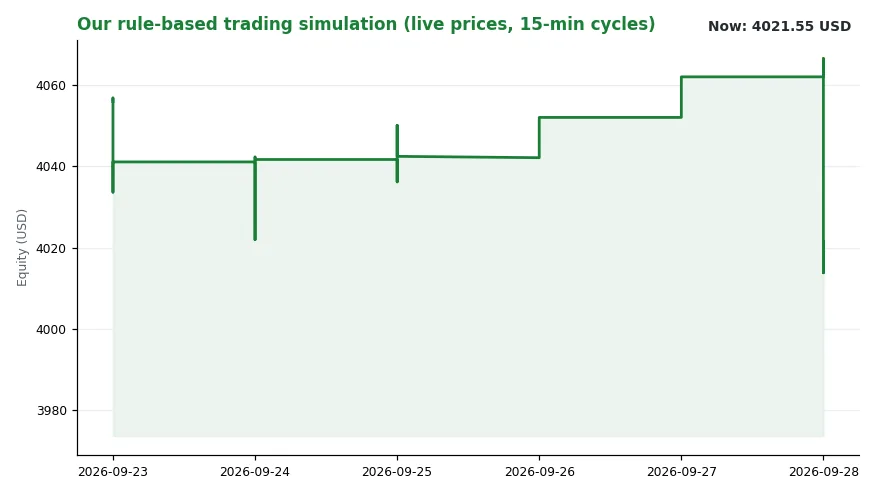
Our simulated book — rule-based, documented without editing — shows equity of 4021.55 USD, down 1.00% versus the same time yesterday, with 1210.27 sitting in cash. The latest logged decision was a BUY of NVDA at 229.28, stamped 2026-09-28 16:52:19. Two details deserve air rather than polish. First, a book that is down 1.00% on a day when one of its holdings is up 2.17% tells you about the rule book, not about the world. Second, the timestamps do not line up: quotes as of 15:57 UTC, a decision stamped 16:52:19. We publish the discrepancy instead of smoothing it.
The signal layer is thin but specific. The busiest channel on 2026-09-27 was “central banks”, with 2 events. Two events is a sample close to noise, and we say so. But it is the only cluster in the data, and it lands the day before our snapshot. The regime reading adds a direction without adding a forecast: trend=falling, level=3.63.
The mechanism, not the mood
Central-bank information reaches a portfolio through the discount rate, not through a fear index. Gold pays no coupon. Its price is a present value discounted at something, which makes it unusually sensitive to the expected path of real yields and to the currency it is quoted in. When policy expectations shift, gold can fall on the worst geopolitical day of the quarter, because the two inputs are simply not the same input. We cannot verify that this is what happened on 2026-09-28 — our data contains no gold-specific attribution — and we will not dress a hypothesis as a finding.
Composition is a second mechanism. An index is a weighting scheme, not an opinion. ^GDAXI near its low at -0.13% is not a verdict on Europe; it is a sum of member prices. KWEB at +0.63%, mid-range, is not a verdict on anything either, but it does tell you the selling was not universal. MSFT at 99% of range while down 1.16% is the useful reminder here: “near the high” and “green” are different measurements, and a range position is a position, not a direction.
Attention is a third. A news front page ranks what editors expect readers to open. It has no obligation to rank what will be traded. The tariff story sits alongside lifestyle and sponsored segments that carry no market signal. None of it is an order book.
Who decides, who pays
On this reading, central banks decide — they are the only clustered channel we can see. The institutions that set the frame also decide something: what a front page leads with shapes what a reader believes the week is about.
Price-wise, over one session only, the bid sat in NVDA at +2.17% and mid-range, and in KWEB at +0.63%, mid-range. Cash holders forfeit nothing and earn little; our sim holds 1210.27 of it. On the other side of the print: gold at 5% of range, TSLA at 11%, KOID at 9%, BTC-USD mid-range but lower. And, measured against yesterday at the same hour, our own rule-based book at -1.00%, having just paid 229.28 for NVDA inside a regime our own reading labels falling. None of this is advice; it is a ledger.
What we watch next
Whether the central-bank channel remains the busiest, or gets displaced. Whether the next regime reading still says falling at level 3.63 — one scalar describing one moment, never a prediction. Whether gold’s 3.91% decline acquires a named cause in the data or stays an observation without an explanation. Whether the NVDA bid at 229.94, mid-range, survives the next print. Whether ^GDAXI, 7% into its range near the low, keeps pretending that a fraction of a percent is flat. The uncertainty is structural: a two-event channel is nearly indistinguishable from noise, a single 15:57 snapshot is one frame of a moving picture, and an equity curve is a log of decisions, not a measure of skill.
What this makes obsolete
- The reflex that a war headline lifts gold mechanically. Our print shows gold at 5% of range, down 3.91%.
- The habit of reading a news site’s front page as a portfolio’s risk register.
- The phrase “risk-off day” as a description of a session in which NVDA rose 2.17% and KWEB rose 0.63%.
- The assumption that a range position implies a direction, when MSFT finished near its high and lower on the day.
- The idea that our own -1.00% says something about markets rather than about our rules.
- The assumption that two timestamps in one document describe one moment.
- The belief that everything published is an input. A tariff story and a lifestyle segment are not the same kind of signal.
Sources
1. Euronews — Quote source (original article)