What a Child Sees in the Gold Line
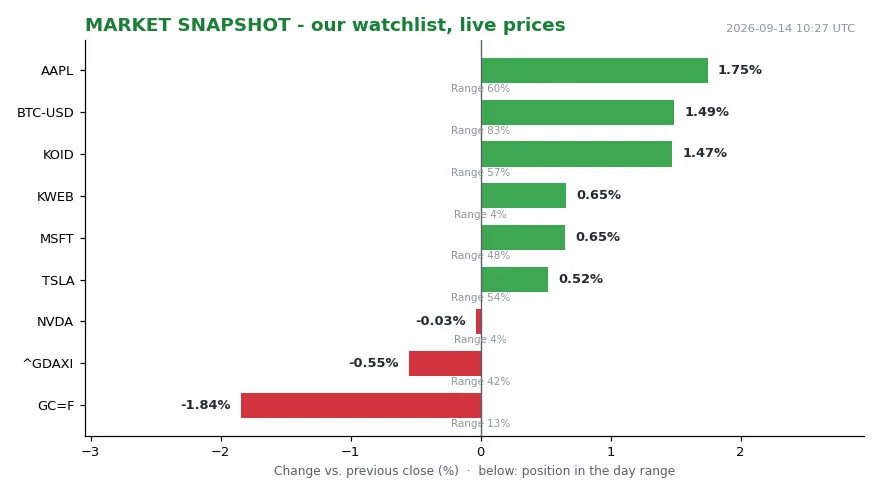
**### Our measurement first, because it is the only thing here we can verify end to end.29 — 0.03 % below its previous close and parked at 4 % of its daily range, meaning the very edge of the day’s low. GC=F, the gold futures contract, traded at 4327.40, down 1.85 % and sitting at 13 % of range, also near the lows. BTC-USD stood at 77970.31, up 1.52 % and near the highs at 84 % of range. AAPL added 1.75 % and held mid-range at 60 %, MSFT added 0.65 % at 48 %, TSLA added 0.52 % at 54 %, and KOID added 1.47 % at 57 %. Two names refused to join: ^GDAXI slipped 0.57 % to sit at 40 % of range, and KWEB rose 0.65 % yet stayed at 4 % of its range, glued to the day’s low. A child reading those nine bars would say something plain: the gold bar shrank while most of the other bars grew. An adult, trained by years of market commentary, would call that noise and wait for a headline to explain it. The noise is the story.
**### The news that never arrived. The page we received from ScienceDirect contains no market information at all. Instead it carries an error message, “There was a problem providing the content you requested”, followed by instructions to contact support, links to remote access and terms, a cookie notice, and a copyright line dated 2026. [1] That copyright line is the most informative sentence on the page: all rights reserved, “including those for text and data mining, AI training, and similar technologies”. [1] So the first fact about this news item is about access, not about prices.
The study applied DCC-GARCH modelling — dynamic conditional correlation inside a GARCH framework — to data from five Asian economies: China, India, Sri Lanka, Bangladesh and Pakistan. Its stated result is a significant connection between gold prices and stock prices, and between gold prices and oil prices, for all of those markets. It adds that the constructs were symmetrical, and then the abstract breaks off mid-sentence with “In general, the connection grow”. That truncation is the boundary of what can be claimed from the record alone.
**### Why this question still matters? Because the question it asks is the question every portfolio asks when it buys gold: does the hedge actually hedge? A hedge is supposed to move against the thing it protects. The idea is old. Gold was the anchor of the Bretton Woods system until 1971, and after the link to the dollar was cut it became a pure reserve asset whose price is set by sentiment, rates and flows. Its reputation as a diversifier was built in specific episodes — the inflation years of the late 1970s, the 2008 credit crisis, the pandemic shock of 2020, when WTI crude famously settled below zero for the first time in history. Each of those episodes taught investors that gold behaves differently when things break. The study is a test of that lesson, and the answer it reports is more uncomfortable than the folklore: the connections run both ways.
If gold, oil and equities share a common, symmetrical linkage, then the protection is weaker and more conditional than the sales pitch suggests. That expectation — that gold diversifies — is priced into allocation decisions everywhere, from sovereign reserves to retail savings plans. Our own regime layer reads trend = falling and level = 3.63, which is a modest, not a dramatic, backdrop. Our sign layer recorded its most active channel on 13 September as “sonst” — other — with 8 events, meaning no single theme dominated the flow.
**### The channel, not the opinion. The first is the discount rate: gold pays no coupon, so when real yields move, gold’s relative appeal moves with them, and equities reprice on the same rate. The second is the dollar and liquidity: a funding squeeze forces sales of whatever is liquid, and gold is liquid. The third is oil as a demand proxy, since crude prices carry information about global activity, and activity drives earnings. The fourth is mechanical rebalancing: when one leg of a portfolio falls, rules-based investors sell what held up. DCC-GARCH exists to measure whether these channels produce correlation that changes over time rather than staying fixed. Symmetry, in that framework, means shocks travel in both directions with comparable strength — oil to gold and gold to oil, equities to gold and gold to equities. That is a statement about co-movement, not about cause. The abstract does not claim causation, and neither should we.
**### Who wins, who loses, who decides. A researcher without a subscription loses twice: once on the article, once on the ability to mine it, given the licensing language on the publisher’s page. Elsevier, as the named rights holder, decides who reads what and on which terms. Allocation and index funds win or lose depending on whether the correlation they assumed still holds. Gold holders lose a little of the comfort they paid for if the symmetry is real, while oil importers and exporters in the five studied economies carry opposite exposures. A reader with only the abstract loses the most important part: the direction in which the connection “grows. Our own simulated book, honestly documented, did nothing. Equity stood at 3972.01 USD, unchanged from the same time the previous day, with cash of 1991.34. The last logged decision was to observe KWEB at 0.00 because the market was closed — observe, not trade, and we record it that way on purpose.
**### What we watch next, and what we do not know. Gold at 13 % of range is one observation, not a trend, and we will not pretend otherwise. KWEB at 4 % of range says Asian internet exposure is being sold even while US technology is bought, but a single minute cannot confirm rotation. Our regime reading of a falling trend at level 3.63 could flip with one session. Then there is the access question: whether the full text becomes readable and the truncated sentence resolves into a number. The uncertainty here is genuine and structural. The study covers five Asian markets and one crisis window, and correlation measured during a crisis is a biased sample of correlation in calm. DCC-GARCH describes the past with precision and the future with none. Our own figures are snapshots from one timestamp, not a time series. None of this is a recommendation to buy or sell anything; it is an analysis of a mechanism.
So the open question is not whether gold, oil and stocks are connected. It is what the word “hedge” can still mean once symmetry is on the table. If a hedge moves with the risk it is meant to hedge, at the same time and with comparable force, it is no longer a hedge — it is another position in the same trade. That is the question the research leaves open.
Sources
1. Elsevier