Fifty Pounds a Month, Untouchable Until 2082
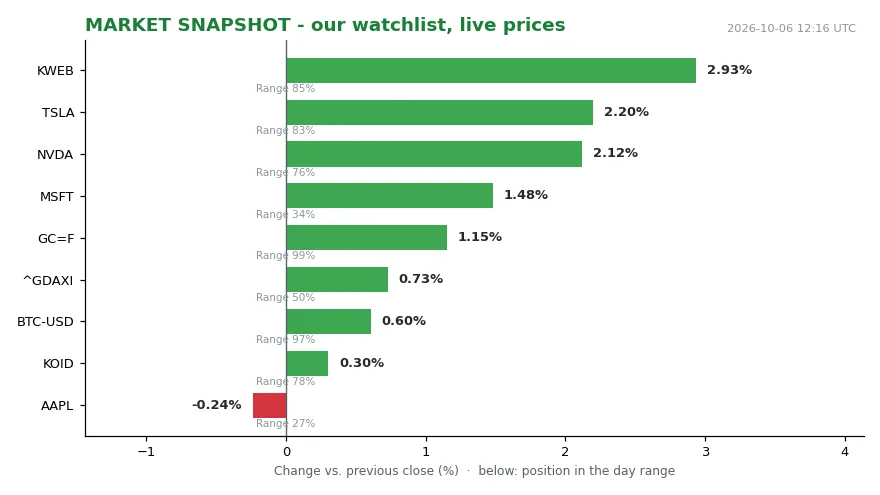
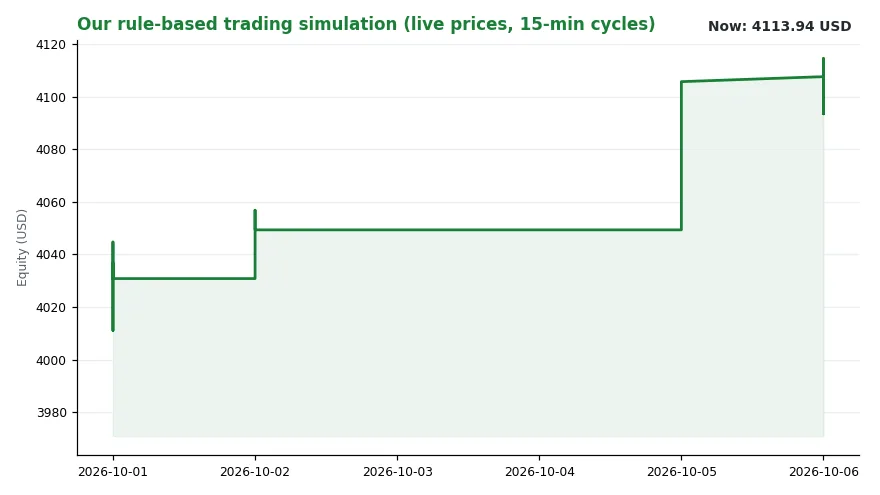
Our own measurement at 12:10 UTC on 6 October 2026: NVDA 238.90, up 2.12% versus the previous close and near the day’s highs at 76% of its range; AAPL 332.89, down 0.24%, mid-range at 27%; MSFT 525.18, up 1.48%, mid-range at 34%; TSLA 378.73, up 2.20%, near the day’s highs at 83%; BTC-USD 86,299.47, up 0.64%, at the top of its range at 100%; gold at 4,202.30, up 1.09%, near the day’s highs at 99%; the DAX at 25,432.24, up 0.70%, mid-range at 46%; KOID 36.85, up 0.30%, near the day’s highs at 78%; and KWEB 24.56, up 2.93%, near the day’s highs at 85%. Our simulated book stands at 4,113.94 USD, up 0.20% versus the same time yesterday, all of it in cash. The latest simulated decision was a SELL of BTC-USD at 86,279.72. The busiest signal channel today is central banks, with one event. The regime reading is trend falling, level 3.63.
That is the tape we read the story against.
The decision that has already been made
Richard Brain is 30. Caitlin Brain is 28. They live in Swansea, in south Wales. Their children are 20 months and five months old. Both already have a private pension in their own name.
The Brains pay £50 a month into each account. Under current UK private pension fund rules, that money cannot be touched until age 57. The elder child reaches 57 in 2082. The younger in 2083.
Richard Brain works for an investment firm. Caitlin Brain is on maternity leave from a job at her local council. Her statutory maternity pay, the legally required paid maternity leave from an employer, of £194 a week has ended. She currently has no income. He earns less than £90,000 a year.
The pensions are only half the architecture. The couple also hold Junior ISAs, tax-free savings accounts for a child accessible at 18, for both children, funded at £60 a month each. That money unlocks at 18. The child-directed total is £220 a month. On top of that, the couple put £200 a month into their own pensions and savings.
The cost shows up in ordinary life. > 1. “We’re not on the breadline, but investing this money does mean doing a little less.” > 2. “We don’t eat out as often as we used to, which as foodies is a pain.” > 3. “And we don’t go as big for one another on birthdays and Christmas so that we can still do it for the kids.”
The mechanism
Junior self-invested personal pensions — Junior SIPPs, self-invested personal pensions opened by an adult on a child’s behalf, where the holder chooses the investments — arrived in the UK in 2001. The wrapper has a hard ceiling. A contributor can pay in £2,880 a year. The government adds £720 in tax relief, the government’s top-up on pension contributions. The total lands at £3,600.
Two forces then do the work. The first is compounding, growth earned on earlier growth as well as on the original money, across an unusually long horizon. The second is the tax relief itself. That relief is a state subsidy attached to every contribution.
Fidelity’s pensions specialist Jemma Slingo supplies the arithmetic. > 4. “Paying in £50 a month from birth, including tax relief, the family would contribute £10,800 over those 18 years. [1] The pot could grow to around £135,000 by retirement. [1]“
> 5. “That’s the real power of starting early - relatively modest amounts can have an exceptionally long time to compound.” That figure is a projection. It is not a guarantee. It depends on contributions continuing for decades. It depends on investment returns nobody can promise in advance.
For providers, the mechanism is simpler. A Junior SIPP is a long-duration asset-gathering product, a wrapper whose money is held for decades. Money enters in infancy. It stays for four or five decades. Fees accrue across that entire span. In our reading, that is why distribution numbers matter more than any single household.
Adoption is climbing. Hargreaves Lansdown reports two and a half times as many accounts opened in the 12 months to April 2026 as in the same period a year earlier. Fidelity reports the number of accounts more than tripled since December 2023.
A wrapper with a latch and a wrapper with a lock
The two account types do different jobs. A Junior ISA carries no tax relief on the way in. It carries no statutory lock past 18. A Junior SIPP carries tax relief on the way in. It carries a hard barrier on the way out.
The Brains use both. The ISA money is aimed at university costs, a business, or a house deposit. The pension money is aimed much further out. That is the clearest statement of intent in the story. > 6. “Paying into their pensions means we can play a part in their future far beyond our own years. And the money has decades to grow.” The access age is not fixed inside the product either. It tracks the normal minimum pension age, the earliest age at which a person may normally draw a private pension, and the government publishes policy on increasing that age. A household projecting a payout in 2083 is projecting against a rule that can be rewritten long before the child turns 57.
In our reading, the children are the eventual winners, and the wait is the price. Hugo Thompson, 15, from Manchester, is one of them. His parents work in finance. They have paid the maximum into his Junior SIPP for the past 10 years. > 7. “The money invested means perhaps I’ll be ahead when I’m older.” > 8. “So I won’t have to put quite so much of my own money in! I want to retire earlier than the state pension age so this will all help.” Not every household can run this play. Hugo’s mother Annabel, who works in finance, sets the boundary herself. She also saves into a Junior ISA for her son. She still invests into her own pension and savings. > 9. “For me, Junior SIPPs should only be considered once you feel you have enough money of your own.” In our reading, that is the sorting rule, and it is also the uncomfortable part. The tax relief is available to anyone with £2,880 to spare per child per year. The compounding is available to anyone who can leave the money alone for five decades. The capacity to do both is not evenly distributed.
Then there is the American comparison. In July this year, US President Donald Trump launched a retirement investment scheme for children called Trump Accounts. Families, friends and employers can contribute up to $5,000, or £3,800, per child per year. The design differs sharply from the UK. Children can access the funds from 18. Withdrawals are subject to taxes, and there is a possible 10% penalty if money is taken before age 59 and a half.
Wally Luckeydoo teaches personal finance at Smyrna High School in Tennessee. He has opened Trump Accounts for his two children, aged four and three.
> 10. “I don’t necessarily think of this as specifically saving for my kids’ retirement. I think of it as giving them a head start and helping change the trajectory of our family financially. [1]“ His reason is personal history. > 11. “My dad passed away when I was very young, and my mom did everything she could to provide for us, often with just the bare minimum.” > 12. “For much of my adult life, I have felt like I was trying to catch up financially, particularly because of significant student loan debt.”
What we watch next
Our own feed gave us a mixed tape, not a single clean signal. So the watchlist here is not one screen of prices. It is three things that can actually be checked.
The first is the age-57 lock. It rests on current UK private pension fund rules. Those rules are published, and they are revisable. If the minimum age moves, the arithmetic for a child born in 2026 moves with it.
The second is flow data. Hargreaves Lansdown and Fidelity have both published growth in account openings. The next provider figures will show whether Junior SIPP adoption is still compounding or has flattened.
The third is the affordability line. Annabel’s rule — secure your own position first — is the constraint that decides whether this stays a behaviour of higher-income households or widens.
The tape we opened with carries the prices. This story travels through flows and fees instead, and those show up in provider disclosures, not in a closing price.
What success looks like is concrete. A child born in Swansea this year turns 57 in 2083. He or she opens a statement and finds a pot assembled from £50 a month, plus tax relief, plus time. Not a windfall. A floor.
Whether that floor exists depends on contributions that cost a family a few restaurant dinners a year. It also depends on rules that no member of that family votes on directly.