Burnham to scrap triple lock from 2030 for social care
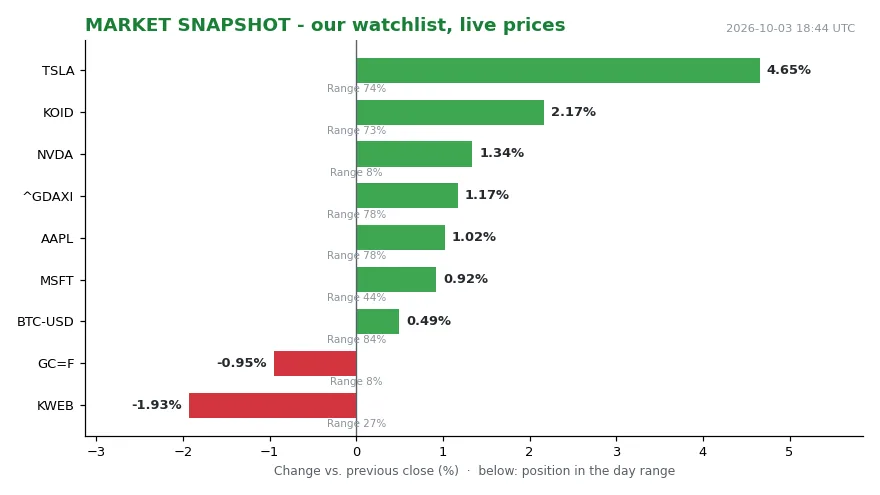
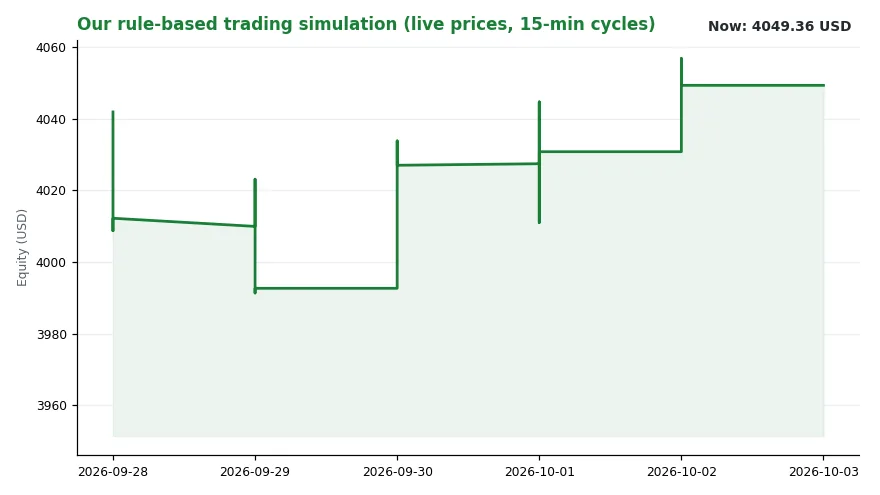
Meta commentary - no external expert source; basis: Feeds.bbci.co.uk (2026-10-03). #MetaEconPol Our watchlist closed mixed on 2026-10-03: NVDA at 233.95 (1.34% vs prev close, near day lows), AAPL at 333.69 (1.02%, near day highs), MSFT at 517.53 (0.92%, mid-range), TSLA at 370.59 (4.65%, mid-range), BTC-USD at 84,934.61 (0.51%, near day highs), gold at 4,162.30 (-0.95%, near day lows), the DAX at 25,231.20 (1.17%, near day highs), KOID at 36.74 (2.17%, mid-range) and KWEB at 23.86 (-1.93%, mid-range). Our sim book stands at 4,049.36 USD, flat versus the same time yesterday, with 2,020.64 in cash; the busiest signal channel on 2026-10-02 was central banks, and the regime reading is trend falling, level 3.63. Against that backdrop, Andy Burnham used his speech to the Labour Party conference to announce that the existing triple lock arrangement (a rule that raises the state pension each year by the highest of inflation, average earnings or 2.5%) will be scrapped from April 2030, with the proceeds directed towards a new plan for social care. The pledge given in Labour’s 2024 manifesto to leave the triple lock untouched for the current Parliament stands, he said. The change lands after it.
That distinction — between the announcement and the implementation date — is where most of the near-term certainty sits. Nothing about a pension paid in 2027 or 2028 or 2029 changes because of this week’s speech. What changes is the shape of the formula that takes over in 2030.
What the mechanism actually does
Under the current arrangement, the state pension rises each April in line with whichever of three measures is highest: CPI inflation (the Consumer Prices Index, the standard measure of UK consumer inflation) in the September of the previous year, average total wage growth including bonuses across the UK for May to July of the previous year, or 2.5%. From April 2030, the guarantee becomes a floor of inflation or 2.5%. The annual link to earnings growth is removed, and is to be reflected over time rather than year by year.
The earnings leg is doing real work right now. Wage growth of 3.9% is likely to determine the April 2027 increase — meaning the flat-rate state pension (the single-tier pension for people who reached pension age after April 2016) would rise to about £250.70 a week, or £13,036.40 a year, up £488. The old basic state pension for those who reached pension age before April 2016 would go to roughly £192.10 a week, or £9,989.20 a year, up £374.40. The government is expected to confirm the figures, possibly in October’s Budget.
For context, the current rates since 6 April 2026 stand at £241.30 a week, or £12,547.60 a year, for the new flat-rate pension, and £184.90 a week, or £9,614.80 a year, for the old basic pension. Many people on the older payment also receive an additional state pension (the extra earnings-related top-up paid alongside the old basic pension) on top.
There is a second channel at work, and it runs through the tax system. The expected April 2027 increase would lift the flat-rate pension above the £12,570 personal allowance (the amount of income on which no income tax is paid), making it liable for about £91 in income tax next year.
Who gains, who loses, who decides
The reform’s most consequential effect is on the savings it generates, and on where those savings go. Burnham’s argument is that the state pension will continue to rise every year at least by inflation or 2.5%.
The Institute for Fiscal Studies called the proposed change a great improvement, saying Burnham had neutered the worst element of the triple lock. [1] Jonathan Cribb, a deputy director at the think tank, said that state pensions would still rise, but more sustainably. [1] He added a caveat that matters for anyone expecting the care plan to be fully financed from this source: the reform should not be expected to save enough to fund universal social care in the next parliament. [1] The Mirror’s reporting carried the headline “I barely make ends meet at 92 - why I still support Burnham’s triple lock axe”, which suggests the politics of the triple lock do not split neatly along the pensioner/non-pensioner line.
The IFS had already argued in July 2025 that the triple lock should be scrapped as part of a wider pensions overhaul, so the political constraint was never the diagnosis — it was the willingness to act on it.
There is a second group of people whose position is shifting independently of this reform. The state pension age (the age at which you may start drawing the state pension) is already rising in two phases: a gradual move to 67 for those born on or after 5 April 1960, and a further move to 68 between 2044 and 2046 for those born on or after 5 April 1977. The first stage began in April 2026; those born between 6 April and 5 May 1960 must wait an extra month. A government review is considering whether to delay the second phase.
For those navigating the contribution rules, the basics are unchanged: 35 qualifying years (years of National Insurance contributions or credits counting towards a full pension) are generally needed for a full state pension, gaps can be filled by voluntary payments, and since April 2025 those payments can only cover the previous six years. Pension credit (a means-tested top-up for the poorest pensioners) remains the gateway to a wider package including housing benefit, council tax reduction and help with heating costs.
What to watch
Three things, in order. First, the confirmed April 2027 uprating (the annual adjustment of benefit and pension rates), expected alongside or near October’s Budget, which will tell us whether the 3.9% wage figure holds. Second, the legislation that defines what “at least inflation or 2.5%” means in practice from 2030 — a floor is only as durable as the drafting behind it. Third, and least certain, the outcome of the review into the second phase of the state pension age; the source attributes the expected saving to the Treasury of about £10bn a year by 2030 to the rise from 66 to 67, not to the outcome of that review.
The £15.5bn annual cost of the guarantee by 2030 is a real number, but it is not the same number as the cost of a national care service, and the gap has not been closed in public. The IFS caveat is the one to hold on to: the reform should not be expected to save enough to fund universal social care in the next parliament.
Sources
Mentioned organisations (context, not sources)
- Labour Party — Organisation (homepage)
- Parliament — Organisation (homepage)
- Institute for Fiscal Studies — Organisation (homepage)
- The Mirror — Organisation (homepage)
BEFUND: Der Artikel behauptet konkrete Marktschlussdaten für den 2026-10-03 für NVDA, AAPL, MSFT, TSLA, BTC-USD, Gold, DAX, KOID und KWEB.
ARTIKEL: “Our watchlist closed mixed on 2026-10-03: NVDA at 233.95 (1.34% vs prev close, near day lows), AAPL at 333.69 (1.02%, near day highs), MSFT at 517.53 (0.92%, mid-range), TSLA at 370.59 (4.65%, mid-range), BTC-USD at 84,934.61 (0.51%, near day highs), gold at 4,162.30 (-0.95%, near day lows), the DAX at 25,231.20 (1.17%, near day highs), KOID at 36.74 (2.17%, mid-range) and KWEB at 23.86 (-1.93%, mid-range).” PRUEFUNG: UNBELEGT BELEG: “nicht gefunden”
BEFUND: Der Artikel behauptet konkrete Werte für das Sim-Buch, Cash, den aktivsten Signal-Kanal am 2026-10-02 und den Regime-Wert.
ARTIKEL: “Our sim book stands at 4,049.36 USD, flat versus the same time yesterday, with 2,020.64 in cash; the busiest signal channel on 2026-10-02 was central banks, and the regime reading is trend falling, level 3.63.” PRUEFUNG: UNBELEGT BELEG: “nicht gefunden”
WIDERLEGT: 0 UNBELEGT: 2