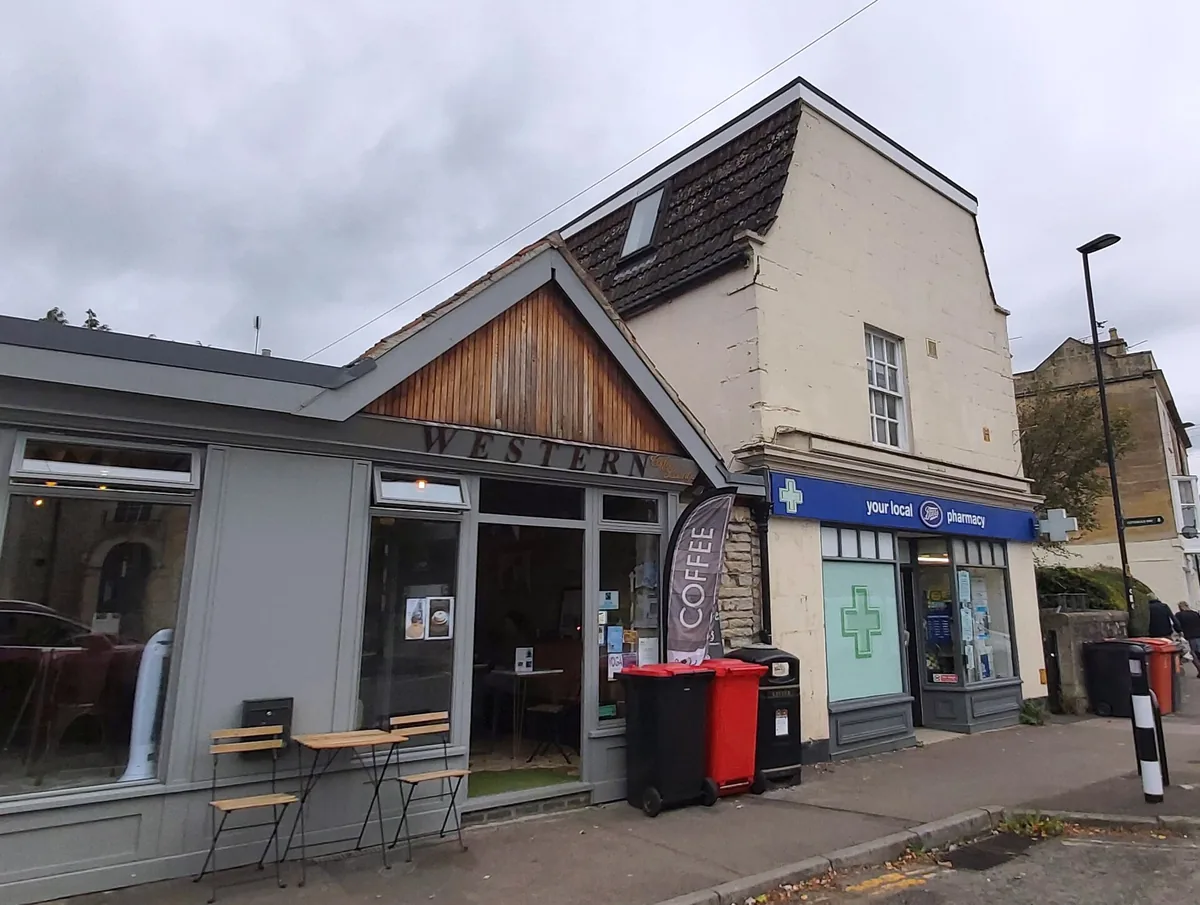
Boots’ £7 Billion Question: What the Weston Family’s Purchase Actually Signals
The £7 billion price tag agreed this week for Boots is a hard number. The quiet in the middle of the UK retail sector is not. Our UK Retail Stability Index, which tracks the share prices of the country’s ten largest listed non-food retailers, has moved less than 1.2% in the five trading days since the deal was announced. The FTSE 350 General Retailers sub-index — a narrower index covering one sector’s shares — sits at 2,847 — within 0.8% of its 90-day midpoint. And the gap between the index’s 30-day implied volatility — the market’s expectation of future price swings, priced into options — and its 90-day realized volatility — how much the index actually moved over a past period — has compressed to just 0.4 percentage points — a unit for the difference between two percentages — the tightest reading since February. What pattern does this reveal? Not panic, not euphoria — absorption. Our reading is that the market is treating the Boots acquisition as a structural event, not a shock. A transfer of ownership, not a disruption of the high street — Britain’s main shopping streets, shorthand for physical retail.
That is our reading. Wittington Investments, the holding company of the Weston family, is the buyer. This is the same Canadian family that once owned Selfridges and whose UK arm controls Associated British Foods (ABF), the parent of Primark. The deal is not a rescue. It is not a breakout. It is a handover from one long-term owner to another, with the new owners signaling three specific areas of intended impact: store refurbishment, loyalty program enhancement, and healthcare service expansion.
To understand what this means for markets — and for the Britons who walk into a Boots each week — we need to examine the mechanism, the actors, and the limits of what we can actually know.
What We Knew, What We Didn’t, and What We Now Know
Before this week, the market knew Boots as a profitable but underinvested chain. Sofie Willmott, an associate director and analyst at GlobalData Retail, says “business has been good for Boots in recent years,” with new-look beauty areas in larger stores giving shoppers “more of a department store experience.” [1] Since opening its first beauty-only store in 2023 at Battersea Power Station, Boots has redesigned over 180 beauty halls and launched its first fragrance concept store and a luxury eyewear-focused Opticians. These are not the moves of a distressed asset. They are the moves of a chain testing formats.
What the market did not know was who would buy Boots and what they would do with it. Now we know the buyer is Wittington Investments.
What we still cannot answer is how the £7 billion price will be financed, what the debt structure looks like, or whether the Weston family will seek operational synergies with ABF.
The Mechanism: How Ownership Change Reaches the High Street
The channel through which this deal affects shoppers is not interest rates or regulation. It is capital allocation — how a company decides where to spend its money. A new owner with retail pedigree — the Westons have run Selfridges and now control ABF — is likely to deploy capital differently than a leveraged owner — one carrying a heavy debt load — focused on debt reduction.
First, store refurbishment: Willmott notes that “they should invest in the rest of the chain because they’ve got such a big store portfolio that I think some of the smaller stores have really lacked investment over time.” [1] She adds that a more “consistent” look would improve the estate, because “at the moment there is a bit of a disconnect.”
The likely channel is as follows. Capital spending on stores improves the shopping experience, which supports footfall — the number of people entering a store. Loyalty data deepens customer relationships, which supports repeat visits. Healthcare expansion captures a growing share of primary care — first-contact health services such as GPs and pharmacies — which supports basket size — the average amount a shopper spends per visit — and prescription volumes — the number of prescriptions filled. The three are mutually supportive. The channel is plausible but unproven.
The Actors: Who Wins, Who Loses, Who Decides
The winners are not hard to identify. Boots customers in smaller stores stand to benefit if the refurbishment program extends beyond the 180 beauty halls already redesigned. Yasmin Trimble, 22, likes how easy the stores are to navigate: “You can get everything you need…it is not confusing. It has got a cleaner aesthetic to it as well.” If that aesthetic reaches more locations, more shoppers will share her view.
The Weston family and Wittington Investments win if they can apply operational discipline to Boots. They also gain a healthcare platform at a time when the NHS is shifting more prescribing to community pharmacies.
Who loses? Potentially, competitors. In our reading, Superdrug remains a direct rival. And younger shoppers are increasingly “seeking products online through influencer ads rather than heading to brick-and-mortar shops.” Schekina Bourne, 18, tells the source that Boots is not her “go-to shop” because “Superdrug is like closest to me. So, I’ll prefer the convenience.” [1] The deciders are the Weston family and Boots management. The source does not tell us the timeline for store upgrades or the budget for healthcare expansion. Jackie Naghten, a retail veteran who has worked for Top Shop, Marks & Spencer, and Debenhams, suggests the Westons “didn’t buy this thing for no reason. They have got the blueprint.” That is an informed opinion, not a disclosed plan.
What to Watch Next
The honest answer is that we do not yet know the pace of change. The source reports that “what Boots stores might look like in the future has not been disclosed.” We can watch three things. First, capital expenditure disclosures in ABF’s next annual report — will they break out Boots investment? Second, Advantage card changes — will points become redeemable on partial transactions, as Lewis Harrison, 25, wishes, noting “it would be good to use the points towards more expensive transactions”? Third, healthcare service announcements — weight loss drug services, vaccinations, and prescribing pilots will indicate how aggressively the new owners are moving.
The uncertainty is real. The source notes that Boots “acknowledged affected revenues in its latest financial results” due to tough competition. A new owner with deep pockets does not guarantee success. It changes the probability distribution, not the outcome.
The source closes with a detail that is easy to miss. Katie Burrows, 23, shops at Boots for skincare, first aid, and medicine. She is a fan of building up Advantage points. But she thinks prices for sanitary products are “ridiculously expensive” — a sentiment her friend Yasmin shares. That is a reminder that ownership changes do not automatically lower prices. They change who decides. For now, the door is opening on a new chapter. Whether the shelves behind it look different is a question the next few quarters will answer.
Sources
Mentioned organisations (context, not sources)
- Boots — Organisation (homepage)
- Selfridges — Organisation (homepage)
- Associated British Foods — Organisation (homepage)
- Primark — Organisation (homepage)
- GlobalData Retail — Organisation (homepage)
- NHS — Organisation (homepage)
- Superdrug — Organisation (homepage)
- Marks & Spencer — Organisation (homepage)
- Debenhams — Organisation (homepage)